USFR
Floating Rate Treasury Fund

Published August 12, 2026

Head of Investment and Fixed Income Strategy

Maggie Lucier
Senior Associate, Investment Strategy
There’s been no summer vacation for the bond market this year. It seems there’s a new headline every day that needs to be processed and responded to. In terms of Treasuries (UST), yields at the back-end of the curve have risen in notable fashion and have resulted in rates being at levels not seen in almost twenty years in some cases. Against this backdrop, we thought it would be useful to help explain what is driving longer-dated Treasury yields higher, and perhaps more importantly, how can fixed income investors position their portfolios.
We have been consistently blogging and podcasting about the impact new Fed Chairman Kevin Warsh has had, and will likely continue to have on UST valuations. The complete lack of forward guidance from Warsh has created an elevated uncertainty quotient for the bond market, resulting in elevated volatility and interest rate (duration) risks. Oftentimes, the yield on maturities such as the ten-year note, carry a term premium, or the extra yield needed to compensate for such uncertainties. Throw this on top of inflation concerns and you get a recipe for higher long-term rates.
Another potential key factor that has flown under the radar but is gaining an increasing amount of attention is the huge rise in debt issuance tied to the massive AI-related buildout. This floodtide of new supply has impacted quite a few fixed income asset classes as investors have witnessed heavy borrowing from hyperscalers and technology companies in the U.S. investment grade and high yield sectors, as well as in the asset-backed securities space. It has been reported that thus far in 2026 AI-related debt issuance alone has been almost $500 billion. Remember, this comes in the wake of elevated Treasury supply in order to fund the nearly $2.0 trillion U.S. budget deficit.
To put things into perspective, since February 27th, the day before the war started, the UST 10-yr yield has increased 75 bps, while the UST 30-yr yield has risen 65 bps, hitting its highest level since June 2007. As we mentioned, adding to the volatility, bond markets are also adjusting to a new Fed under Chair Kevin Warsh. In our previous blog, “A New Warsh Cycle” we discussed our Zero Duration Suite as a way for bond investors to position themselves amid that uncertainty.
There’s good reason to think rates could move higher still, particularly as bond supply across the market continues to grow. We still do not see a noteworthy bond market rally anytime soon, and technical analysis suggests that we are not oversold yet. So, what should fixed income investors do from here?
Our Zero Duration Suite (USFR, AGZD, HYZD) is built to help limit duration risk across different sectors of the bond market. The performance in the current environment, outlined below highlights how our Zero Duration suite has visibly outperformed the .
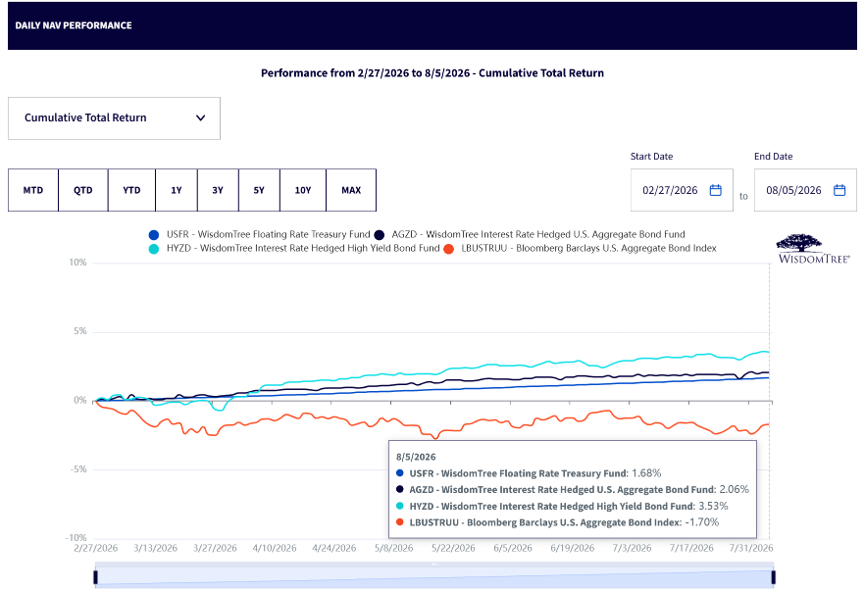
Source: WisdomTree, as of 8/6/2026. Past performance is not indicative of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance data quoted. For the most recent month-end and standardized performance and to download the respective Fund prospectuses, click the relevant ticker: USFR, AGZD, HYZD.
WisdomTree Floating Rate Treasury Fund (USFR): Treasury notes without duration. Its rate resets weekly, so it rides along with rising rates instead of being impacted by them.
WisdomTree Interest Rate Hedged U.S. Aggregate Bond Fund (AGZD): the Agg without duration. Reference the benchmark to understand duration’s effect in a volatile, rising rate environment.
WisdomTree Interest Rate Hedged High Yield Bond Fund (HYZD): quality screened high yield, zero duration. Designed to keep the plus component of high-yield bonds but strips out the rate risk that can affect the sector.
While the July jobs report came in softer than expected, it did not change the bond market narrative looking ahead. Interestingly, the July employment data is potentially eerily similar to what transpired during the summers of 2024/2025…cooler than expected payrolls and downward revisions, only to rebound later?
Unlike the prior two years’ experiences, the cooler new hiring numbers will not be followed by three straight Fed rate cuts. In fact, unless upcoming inflation data suggest otherwise, the monetary policy tilt for the bond market is still skewed toward a rate hike.
There are risks associated with investing, including possible loss of principal. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
USFR: Securities with floating rates can be less sensitive to interest rate changes than securities with fixed interest rates, but may decline in value. Fixed income securities will normally decline in value as interest rates rise. The value of an investment in the Fund may change quickly and without warning in response to issuer or counterparty defaults and changes in the credit ratings of the Fund’s portfolio investments. Due to the investment strategy of this Fund it may make higher capital gain distributions than other ETFs. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit, and the Fund does not attempt to outperform its Index.
AGZD: Fixed income investments are subject to interest rate risk; their value will normally decline as interest rates rise. The Fund seeks to mitigate interest rate risk by taking short positions in U.S. Treasuries (or futures providing exposure to U.S. Treasuries), but there is no guarantee this will be achieved. Derivative investments can be volatile and these investments may be less liquid than other securities, and more sensitive to the effects of varied economic conditions. Fixed income investments are also subject to credit risk, the risk that the issuer of a bond will fail to pay interest and principal in a timely manner, or that negative perceptions of the issuer’s ability to make such payments will cause the price of that bond to decline. The Fund may engage in “short sale” transactions of U.S. Treasuries where losses may be exaggerated, potentially losing more money than the actual cost of the investment and the third party to the short sale may fail to honor its contract terms, causing a loss to the Fund. While the Fund attempts to limit credit and counterparty exposure, the value of an investment in the Fund may change quickly and without warning in response to issuer or counterparty defaults and changes in the credit ratings of the Fund’s portfolio investments. Investing in mortgage- and asset-backed securities involves interest rate, credit, valuation, extension and liquidity risks and the risk that payments on the underlying assets are delayed, prepaid, subordinated or defaulted on. Due to the investment strategy of the Fund, it may make higher capital gain distributions than other ETFs. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index.
HYZD: High-yield or “junk” bonds have lower credit ratings and involve a greater risk to principal. Fixed income investments are subject to interest rate risk; their value will normally decline as interest rates rise. The Fund seeks to mitigate interest rate risk by taking short positions in U.S. Treasuries (or futures providing exposure to U.S. Treasuries), but there is no guarantee this will be achieved. Derivative investments can be volatile and these investments may be less liquid than other securities, and more sensitive to the effects of varied economic conditions.
Fixed income investments are also subject to credit risk, the risk that the issuer of a bond will fail to pay interest and principal in a timely manner, or that negative perceptions of the issuer’s ability to make such payments will cause the price of that bond to decline. The Fund may engage in “short sale” transactions where losses may be exaggerated, potentially losing more money than the actual cost of the investment and the third party to the short sale may fail to honor its contract terms, causing a loss to the Fund. While the Fund attempts to limit credit and counterparty exposure, the value of an investment in the Fund may change quickly and without warning in response to issuer or counterparty defaults and changes in the credit ratings of the Fund’s portfolio investments. Due to the investment strategy of the Fund, it may make higher capital gain distributions than other ETFs. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index.


Head of Investment and Fixed Income Strategy
Kevin serves as the Head of Investment and Fixed Income Strategy. In this role, he writes macro and fixed income-related content and works closely with the sales, research and marketing teams. In addition, Kevin conducts client-facing webinars and meetings, providing expertise on WisdomTree’s existing and future bond ETFs. Prior to joining WisdomTree, Kevin spent 30 years at Morgan Stanley, where he was Managing Director and Chief Fixed Income Strategist for Wealth Management. He was responsible for tactical and strategic recommendations and created asset allocation models for fixed income securities. He was a contributor to the Morgan Stanley Wealth Management Global Investment Committee, primary author of Morgan Stanley Wealth Management’s monthly and weekly fixed income publications, and collaborated with the firm’s Research and Consulting Group Divisions to build ETF and fund manager asset allocation models. Kevin has an MBA from Pace University’s Lubin Graduate School of Business, and a B.S. in Finance from Fairfield University.

Senior Associate, Investment Strategy
Maggie Lucier is a Senior Associate on WisdomTree’s Investment Strategy team. Maggie brings a client-first perspective where she develops and communicates market insights, investment themes, and portfolio perspectives to clients and colleagues across the firm. In addition, she is responsible for the planning and implementation of Office Hours, WisdomTree’s ongoing webinar series for financial advisors. Prior to her current role, she served on WisdomTree's Sales team working directly with clients, an experience that informs how she conveys complex ideas into actionable solutions. Maggie holds a B.S. in Business and Enterprise Management from Wake Forest University.