

There’s a New Kid in Town in the Bond Market
Published November 5, 2026

Kevin Flanagan
Head of Investment and Fixed Income Strategy

Maggie Lucier
Senior Associate, Investment Strategy
Key Takeaways
- Artificial intelligence (AI) and tech concerns have renewed safe-haven demand for Treasuries, helping lower yields even as the pressures that drove them higher persist.
- The recent 40-basis-point decline in the 10-year Treasury yield has left yields at higher lows, with absolute levels still elevated.
- Solid growth, above-target inflation, Federal Reserve (Fed) policy uncertainty and debt supply could reassert their influence on Treasury yields as safe-haven demand fades.
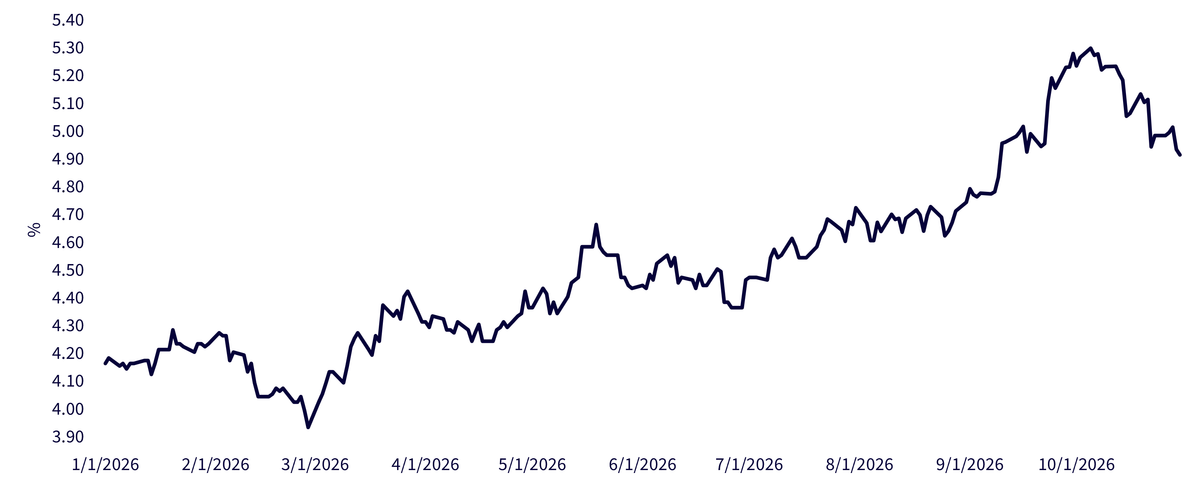
After surging to its highest level in more than 20 years earlier this month, the U.S. Treasury (UST) 10-year yield has made a visible U-turn over the last few weeks. Interestingly, the forces we have discussed that pushed longer-date Treasury yields to their recent peaks have not gone away, leaving investors with the quandary of what happened then. In our opinion, the answer is pretty straightforward: there’s a new kid in town.
Who is “the new kid,” or shall we say, force impacting the bond market? Without a doubt, it has been the renewed safe-haven bid for Treasuries among the global investment community stemming from the risk-off AI/tech-related wave of anxieties. This flight-to-quality bid was also enhanced by short-covering from market participants who were positioned for long-term UST yields to rise further.
Figure 1: U.S. Treasury 10-Year Yield
Source: Bloomberg, as of 10/30/2026.
As the above graph reveals, this safe-haven bid was also present before the Middle East war when private credit and business development company (BDC) concerns were dominating the narrative and the UST 10-year yield fell to 3.94%, or 100 basis points below current levels, as of this writing. That is the important aspect to remember for fixed income investors: even with the recent 40-basis-point rally in the 10-year, absolute yield levels are now much higher, with such rallies only producing “higher lows.”
Once things settle down and the safe-haven bid fades, attention will shift back to the four forces we have continued to highlight. So, let’s take a look at where they stand:
- Solid Growth
- Recent data suggest the labor market is fine and steady: the unemployment rate has leveled around 4.2% and weekly jobless claims remain near multi-decade lows below 200,000.
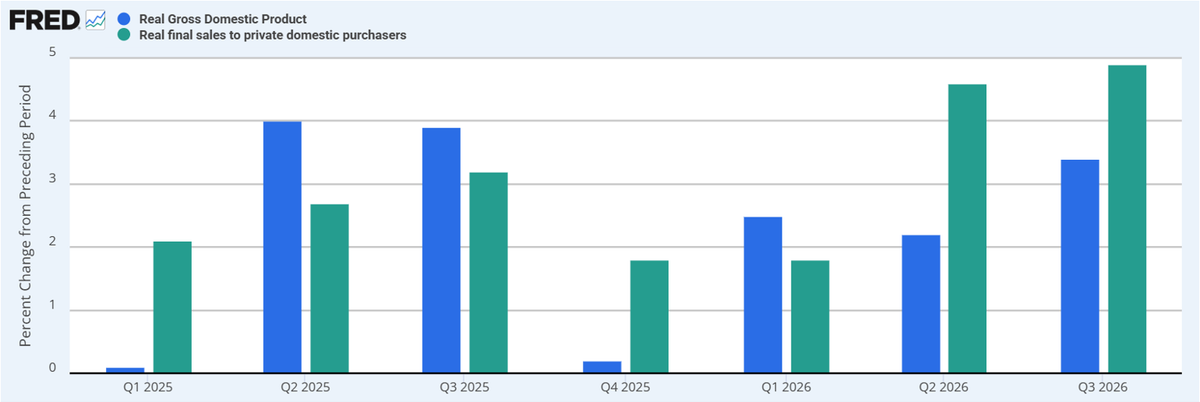
- In the third quarter, real gross domestic product (GDP) grew 3.4% and real final sales to private domestic purchasers accelerated by 4.9%.
- Consumer spending and private investment remain very solid and will give the economy momentum heading into year-end.
Figure 2: U.S. Economic Growth
Source: U.S. Bureau of Economic Analysis via FRED.
- “Sticky,” Above Fed-Target Inflation
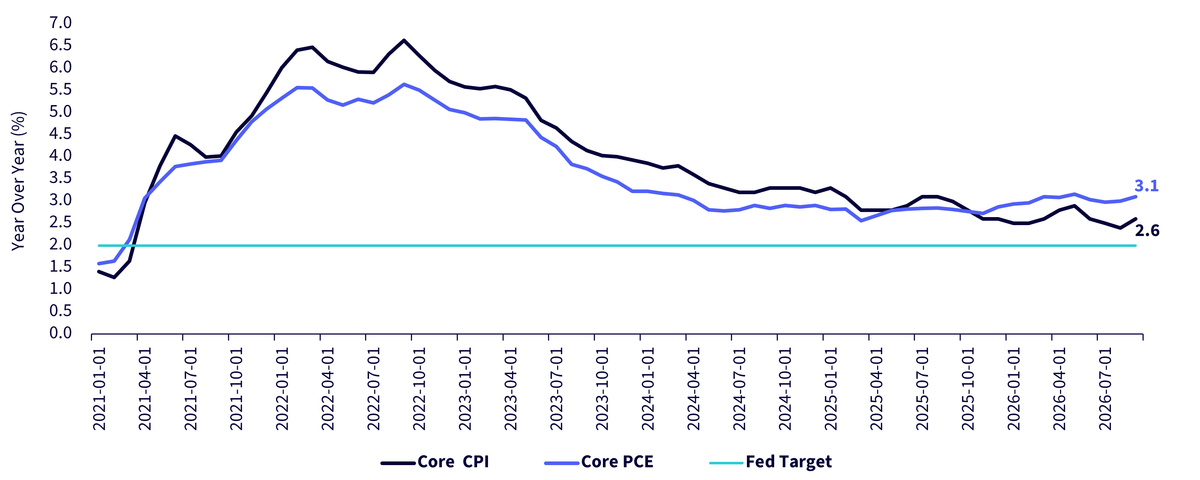
- The September readings for the consumer price index (CPI), producer price index (PPI) and personal consumption expenditures (PCE) all came above the Fed’s target of 2%.
- September core CPI (2.6% year over year) and PPI (6.3% year over year) both came in hotter than expected, while core PCE (3.1% year over year) matched expectations.
- We expect higher energy prices to keep passing through to other areas and the AI buildout to continue applying upward pressure on prices.
Figure 3: Core Inflation
Source: Bloomberg, as of 10/30/2026.
- The “Warsh-Uncertainty” Factor
- Removal of forward guidance has created elevated policy uncertainty.
- Adding to this uncertainty will be the change in the 2027 Federal Open Market Committee (FOMC) meeting schedule, where one meeting will not have a vote or policy statement.
- As a result, the bond market wants a higher term premium (higher yield compensation).
- Supply, Supply, Supply
- The U.S. budget deficit rose to just about $2 trillion for fiscal year 2026, and Treasury will need to increase coupon auction sizes going forward.
- Based on recent Treasury forward guidance, any potential increase in coupon auction size could come by mid-2027 and could be concentrated in the 2- to 10-year sector.
- Despite higher long-term rates and recent AI/tech-related setbacks, funding needs for the AI buildout will continue to require more debt issuance.
Conclusion
It seems highly likely that the forces which pushed the UST 10-year yield to a more than 20-year high-water mark are not going away anytime soon. While the “new kid in town” may put a cap on rates in the near term, once the AI/tech-related selloff fades, the old-school factors should still have a visible impact on the UST 10-year yield moving forward.
Categories


About the contributors

Kevin Flanagan
Head of Investment and Fixed Income Strategy
Kevin serves as the Head of Investment and Fixed Income Strategy. In this role, he writes macro and fixed income-related content and works closely with the sales, research and marketing teams. In addition, Kevin conducts client-facing webinars and meetings, providing expertise on WisdomTree’s existing and future bond ETFs. Prior to joining WisdomTree, Kevin spent 30 years at Morgan Stanley, where he was Managing Director and Chief Fixed Income Strategist for Wealth Management. He was responsible for tactical and strategic recommendations and created asset allocation models for fixed income securities. He was a contributor to the Morgan Stanley Wealth Management Global Investment Committee, primary author of Morgan Stanley Wealth Management’s monthly and weekly fixed income publications, and collaborated with the firm’s Research and Consulting Group Divisions to build ETF and fund manager asset allocation models. Kevin has an MBA from Pace University’s Lubin Graduate School of Business, and a B.S. in Finance from Fairfield University.

Maggie Lucier
Senior Associate, Investment Strategy
Maggie Lucier is a Senior Associate on WisdomTree’s Investment Strategy team. Maggie brings a client-first perspective where she develops and communicates market insights, investment themes, and portfolio perspectives to clients and colleagues across the firm. In addition, she is responsible for the planning and implementation of Office Hours, WisdomTree’s ongoing webinar series for financial advisors. Prior to her current role, she served on WisdomTree's Sales team working directly with clients, an experience that informs how she conveys complex ideas into actionable solutions. Maggie holds a B.S. in Business and Enterprise Management from Wake Forest University.