

Higher Bond Yields Go Global
Published September 30, 2026

Kevin Flanagan
Head of Investment and Fixed Income Strategy

Maggie Lucier
Senior Associate, Investment Strategy
Key Takeaways
- Global sovereign yields surged to multi-year highs last week—with the U.S. 10-year Treasury reaching 5.2%, the highest since 2007—underscoring the need for investors to reassess duration and global fixed income exposure.
- Deficit spending, persistent inflation concerns and renewed central bank tightening are pushing yields higher across the US, Japan, Germany and the UK
- Treasuries should remain a key global allocation, but rising domestic yields are giving Japanese and other foreign investors more incentive to keep funds at home
The sell-off in U.S. Treasury (UST) yields has continued pretty much in an unabated fashion In fact, multi-year high watermarks are being achieved throughout the fixed coupon maturity curve. The most widely followed development was the UST 10-year yield rising to its highest level since 2007.
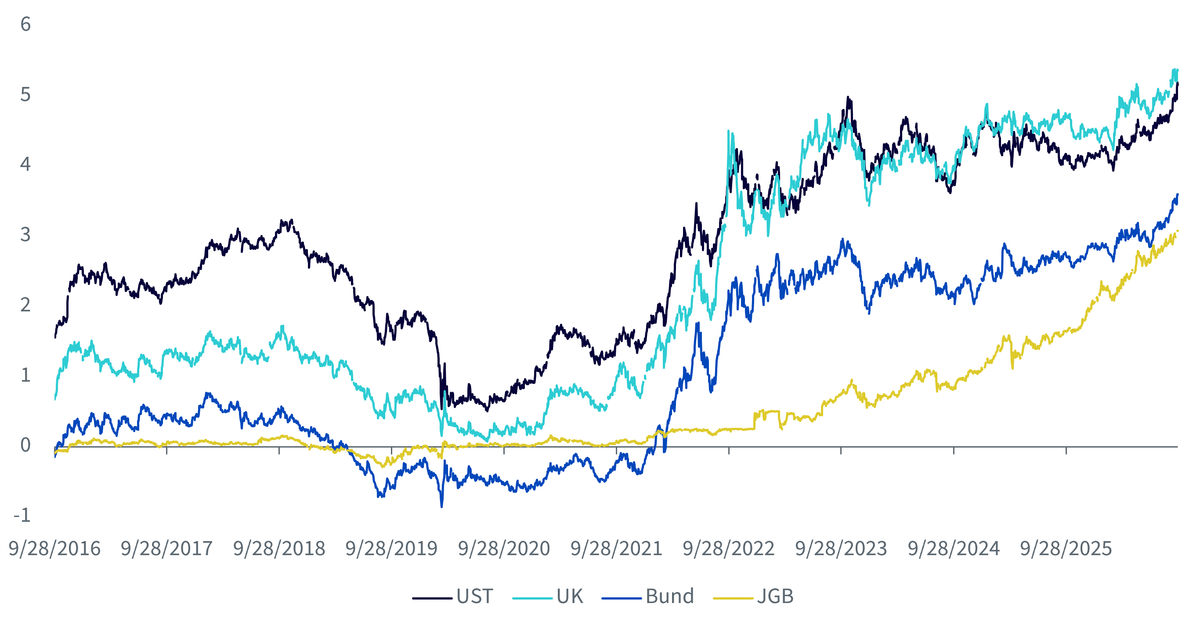
Interestingly, this soaring rate phenomenon has not been isolated to only the U.S. government bond market as sovereign debt yields have risen in a noteworthy fashion all around the key developed countries. As has been the case in the U.S., a number of foreign government bond yields have also reached multi-decade highs. Here’s some context:
- UST 10-year hit its 19-year high at 5.2% (2007)
- Japanese 10-year JGB hit its 30-year high at 3.06% (1996)
- German 10-year Bund hit its 15-year high at 3.60% (2011)
- UK 10-year Gilt hit its 18-year high at 5.36% (2008)
With these bond yields at their highest levels since the early 2000s, you may be wondering, what exactly happened to the global bond market last week? Let’s break it down.
10-Year Government Bond Yields
Source: Bloomberg, as of 9/27/2026
Source: Bloomberg, as of 9/27/2026
Overall, three main factors are affecting these major global bond markets. The U.S., Europe and Japan are exposed to:
- Deficit spending
- Inflation concerns
- Central bank tightening
Simply put, deficit spending can stoke inflation and result in central bank rate hikes to counter current and/or future demand pressures. Unfortunately, these factors do not seem as if they are disappearing for quite some time, which ultimately may make those deficits even more expensive to finance.
U.S.
As we have previously written in What’s Driving Treasury Yields Higher?,there are varying factors that are impacting U.S. Treasury Yields. On top of sticky inflation, a resilient economy, the Warsh term premium and crowding out effects, the U.S. government deficit has pushed investors to demand higher yields on longer-dated Treasury bonds. Notably, two of the UST auctions last week showed weak demand, showing perhaps that current yield levels are still not overly enticing for investors.
Japan
After residing in negative territory and then being capped out under 1%, ten-year JGBs have now surpassed the 3% threshold, due to Bank of Japan (BOJ) tightening and dialed-up fiscal spending plans. Japan’s position is of particular importance because it’s historically been one of the world’s largest government debt buyers. However, given rising currency hedging costs and relatively more attractive yields in their own domestic bond market, Japanese life insurers and pension funds may now see more incentive to keep their funds at home.
Germany
Rising energy costs from the Middle East conflict have ignited inflation concerns, driving the European Central Bank (ECB) into rate-hike mode. As a result, Bund yields hit their highest levels since 2011. As we have witnessed here in the U.S., the bund market had not been anticipating ECB rate hikes at all. Now traders are projecting several hikes through 2027.
UK
The 10-year Gilt yield moved closer to multi-year highs, and the market is expecting a 25-basis point rate hike from the Bank of England in November. On top of that, their debt levels are rising close to 95% of GDP, which is triple what it was before the Global Financial Crisis. They are also carrying one of their heaviest debt burdens in more than half a century.
Conclusion
Some market commentary has questioned whether the UST market remains a key source for global investors. The answer is yes. However, with the rise in other sovereign debt market yields, Treasuries do have some potential competition. Rather than foreign investors becoming active sellers of Treasuries, we see the most likely scenario being one of continued foreign buying, but perhaps at a somewhat lesser rate.
Categories
Related articles

The Results Are in…Now on to 2028
There’s a New Kid in Town in the Bond Market

Fed Watch: Holding the Line
Investing in a 5% Bond World: The Barbell
“Zero-ing” In on Higher Bond Yields

The Return of the De-Dollarization Theme? Winners and Losers in the $40 Trillion Debt Era
Fed Watch: Finally, ‘Walkin’ the Walk’
AI’s Growing Debt Appetite: Why This Time May Be Different
The Bond Market Is Just Doing Its Job
About the contributors

Kevin Flanagan
Head of Investment and Fixed Income Strategy
Kevin serves as the Head of Investment and Fixed Income Strategy. In this role, he writes macro and fixed income-related content and works closely with the sales, research and marketing teams. In addition, Kevin conducts client-facing webinars and meetings, providing expertise on WisdomTree’s existing and future bond ETFs. Prior to joining WisdomTree, Kevin spent 30 years at Morgan Stanley, where he was Managing Director and Chief Fixed Income Strategist for Wealth Management. He was responsible for tactical and strategic recommendations and created asset allocation models for fixed income securities. He was a contributor to the Morgan Stanley Wealth Management Global Investment Committee, primary author of Morgan Stanley Wealth Management’s monthly and weekly fixed income publications, and collaborated with the firm’s Research and Consulting Group Divisions to build ETF and fund manager asset allocation models. Kevin has an MBA from Pace University’s Lubin Graduate School of Business, and a B.S. in Finance from Fairfield University.

Maggie Lucier
Senior Associate, Investment Strategy
Maggie Lucier is a Senior Associate on WisdomTree’s Investment Strategy team. Maggie brings a client-first perspective where she develops and communicates market insights, investment themes, and portfolio perspectives to clients and colleagues across the firm. In addition, she is responsible for the planning and implementation of Office Hours, WisdomTree’s ongoing webinar series for financial advisors. Prior to her current role, she served on WisdomTree's Sales team working directly with clients, an experience that informs how she conveys complex ideas into actionable solutions. Maggie holds a B.S. in Business and Enterprise Management from Wake Forest University.