DXJ
Japan Hedged Equity Fund

Published August 12, 2026

Global Head of Research

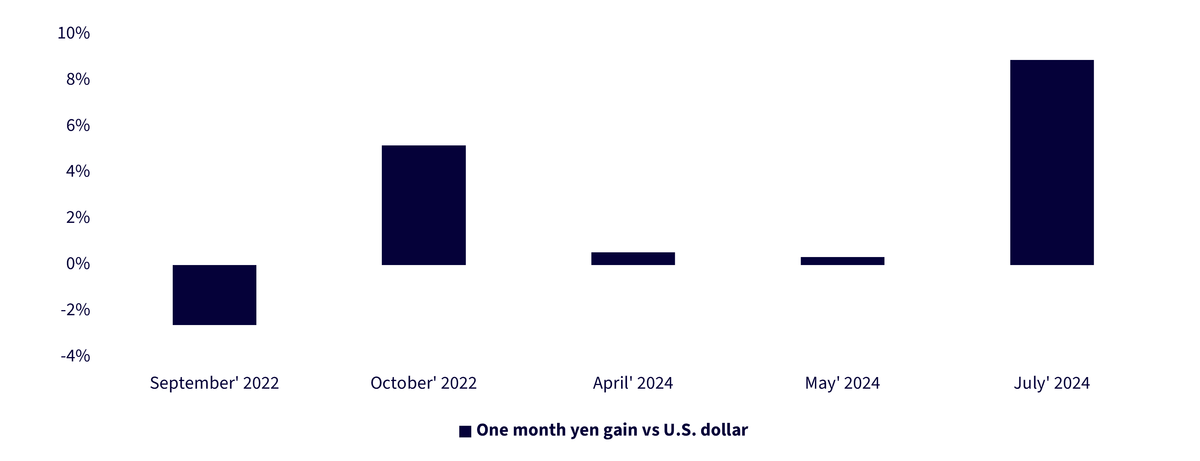
Japan’s Ministry of Finance has repeatedly intervened to support the yen over the past four years. Until now, the pattern has been familiar. Authorities stepped in, the currency rallied briefly, and depreciation resumed once markets returned to the underlying interest rate differential.1
The latest intervention felt different. The move was larger, the market reversal was sharper, and Japan received support from the U.S. That combination gives the intervention more credibility than prior unilateral efforts. Even so, it does not remove the central problem. A durable yen recovery will ultimately require help from the Bank of Japan (BoJ).
Japan began its current intervention cycle in September 2022, when it bought yen for the first time since 1998. Since then, the Ministry of Finance has reportedly spent at least ¥22trn (US$139bn) supporting the currency, excluding the latest operation. Despite that commitment, the yen continued to weaken as the return available on dollar assets remained substantially higher than that on comparable Japanese assets.2
Bloomberg Finance L.P., WisdomTree as of July 31, 2026. Past performance is not indicative of future results.
The estimated US$52.8bn deployed would represent the largest single day intervention on record.3 Its timing and scale indicate that the authorities are becoming less willing to tolerate disorderly depreciation. The Yen rose by 3.78% during the initial move, its sharpest 1-day advance in multiple years.4
The changing intervention threshold is also revealing. Four years ago, markets appeared to treat roughly ¥145 per dollar as an important line for policymakers. The latest action came much closer to ¥160, suggesting that investors had become increasingly confident in testing the authorities’ resolve. That confidence may now be less secure.
The intervention carried more weight because Japan did not act entirely alone. U.S. involvement reportedly included rate checks and coordinated yen purchases, signaling that Washington is also concerned about the consequences of uncontrolled depreciation.
The U.S. has several reasons to support Japan. A sharp fall in the yen could destabilize Japanese government bonds, encourage Japanese institutions to sell overseas assets, and place upward pressure on U.S. Treasury yields. Japan is one of the largest foreign holders of U.S. government debt, so the stability of Japanese markets has direct implications for U.S. financial conditions.
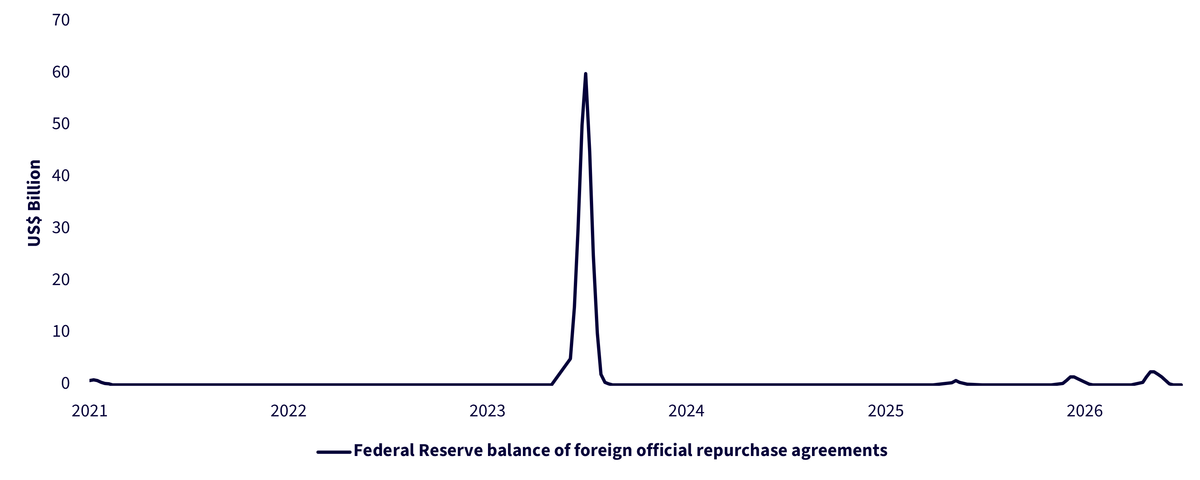
The Federal Reserve’s (Fed) Foreign and International Monetary Authorities Repo Facility, known as FIMA, could make future intervention easier to finance. Scott Bessent described the FIMA program as an important support for Japan’s efforts and said: “We would encourage it to be upsized in the coming months.”5 Japan can pledge U.S. Treasury securities in exchange for dollars rather than selling those bonds outright. The dollars can then be exchanged for yen.
Source: Federal Reserve, Bloomberg Finance L.P., WisdomTree, as of July 31, 2026.
This approach reduces the risk that intervention itself causes a selloff in U.S. Treasuries. It is an important improvement in the mechanics of currency support, although it does not change the fundamentals determining the exchange rate.
The yen’s importance extends far beyond Japan. For years, investors have borrowed at low Japanese interest rates and invested the proceeds in higher-yielding currencies and assets. This carry trade has been one of the most reliable strategies in global markets, benefiting from both the yield differential and persistent yen weakness.
A sudden appreciation changes the calculus. Investors with short yen positions may be forced to buy the currency to close their trades, reinforcing the initial rally. That feedback loop can become disorderly, particularly when positioning is crowded.
The recent intervention had already interrupted what had been a remarkably steady carry trend. The ¥155 per dollar level is a potentially important threshold.6 A sustained break below that level could trigger stop losses and encourage Japanese exporters to convert more overseas revenues into yen. This is one reason the latest intervention may prove more effective than previous attempts in the short run. It arrived alongside broader dollar weakness, crowded positioning and increasing official coordination.
Currency intervention works by altering the immediate supply and demand balance, signaling policymakers’ discomfort and raising the cost of speculative positions. It can be particularly effective when it pushes the market through widely watched technical or corporate planning levels.
The BoJ’s Tankan survey suggests that many Japanese companies have based their current fiscal year assumptions on exchange rates around ¥150 to ¥155 per dollar.7 A sustained move below that range could lead exporters to sell dollars more actively, adding private-sector support to official intervention.
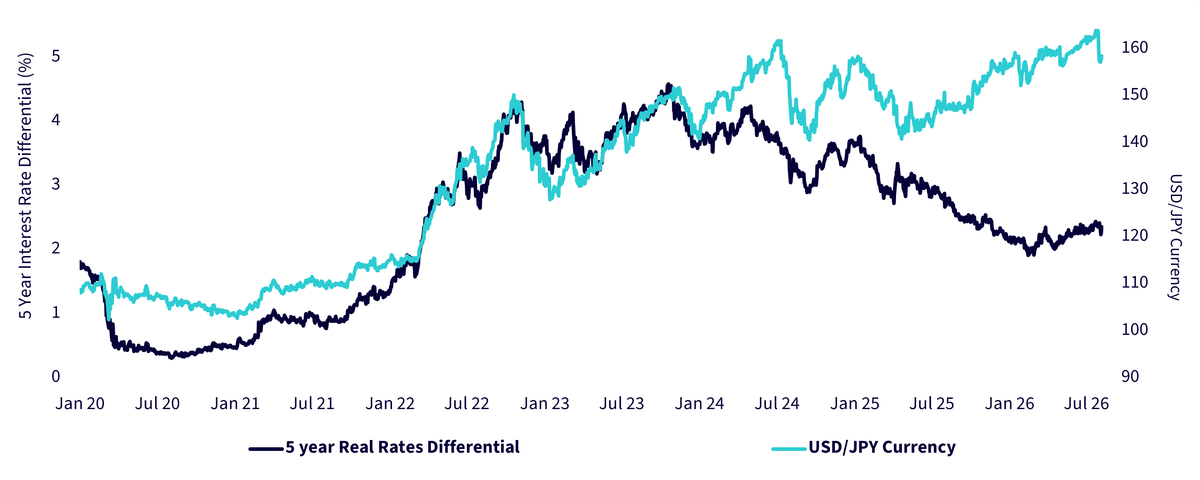
But the interest rate differential remains the dominant longer-term force. The yen’s depreciation has closely tracked the widening gap between expectations for U.S. and Japanese monetary policy. If the Fed maintains or even raises rates while the BoJ tightens only slowly, dollar assets continue to offer a large yield advantage.
Source: Bloomberg Finance L.P., WisdomTree as of August 6, 2026.
Amidst the ongoing conflict in Iran, higher oil prices compound the pressure. Japan imports most of its energy, so rising crude prices increase demand for dollars and worsen the country’s terms of trade. At the same time, Prime Minister Sanae Takaichi’s growth-focused fiscal policy may support activity but also reinforce concerns about inflation and public finances. These forces are less likely to be offset by buying yen in the market.
The BoJ raised its policy rate to 1% in June, the highest level since 1995, but then held steady.8 Market expectations still point to a limited number of further hikes, despite the inflationary risks created by energy prices and yen weakness.
That cautious stance explains why intervention alone faces a credibility problem. If the central bank remains reluctant to narrow the yield gap, investors may eventually rebuild short yen positions once the immediate fear of further intervention fades.
The intervention creates a bridge to faster tightening. Authorities can stabilize the currency first, then reinforce that move with a more hawkish BoJ path. This would give investors a fundamental reason to hold yen rather than merely fear official action. If inflation remains persistent, wage growth stays firm and the yen again weakens sharply, the pressure on the BoJ to accelerate normalization is likely to rise. The intervention may reinforce expectations for future rate increases while USD/JPY remains in the ¥150s.
Without that follow-through, the intervention is more likely to buy time than create a new currency regime.
The WisdomTree Japan Hedged Equity Fund (DXJ) focuses equity exposure on dividend-paying, globally-oriented businesses of Japan. Any movement in the Japanese yen versus the U.S. dollar is neutralized from a returns perspective, leaving investors with the return stream of the underlying equities. Importantly, positioning the currency hedge for U.S. investors also allows them to collect the interest rate differential, which we mentioned above, so long as U.S. interest rates are higher than those in Japan.
The WisdomTree Japan Opportunities Fund (OPPJ) creates a diversified array of potential avenues to benefit from a Japanese equity exposure. The four distinct sleeves include:
OPPJ also has a dynamic currency hedge that can be adjusted on a monthly basis.
At WisdomTree, we continue to see strong opportunity in the underlying fundamentals of Japan’s equity market, and this remains the key driver that is the catalyst for our interest in this market.
1 Source: Ministry of Finance Japan. (n.d.). Foreign exchange intervention operations.
2 Source: Ministry of Finance Japan. (n.d.). Foreign exchange intervention operations.
3 Source: Bloomberg News. (2026, July 31). BOJ data suggest Japan intervention of about 8.45 trillion yen. Bloomberg.
4 Source: Bloomberg News. (2026, July 30). Japan's yen posts biggest gain since April as market eyes possible intervention. Bloomberg.
5 Source: Bessent, S. [@SecScottBessent]. (2026, August 2). The Trump Administration delivers for America's trusted partners... [Post]. X.
6 Source: Bloomberg News. (2026, August 4). After historic intervention, 155 emerges as yen's next big test [Video]. Bloomberg.
7 Source: Bank of Japan. (2026, July 1). Tankan outline (June 2026).
8 Source: Bank of Japan. (2026, June 16). Change in the guideline for money market operations [PDF].
9 Source: Buffett, W. E. (2024). 2023 annual report: Letter to shareholders. Berkshire Hathaway Inc.
There are risks associated with investing, including possible loss of principal. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
DXJ: Foreign investing involves special risks, such as risk of loss from currency fluctuation or political or economic uncertainty. The Fund focuses its investments in Japan, thereby increasing the impact of events and developments in Japan that can adversely affect performance. Derivative investments can be volatile and these investments may be less liquid than other securities, and more sensitive to the effect of varied economic conditions. As this Fund can have a high concentration in some issuers, the Fund can be adversely impacted by changes affecting those issuers. Due to the investment strategy of this Fund, it may make higher capital gain distributions than other ETFs. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index.
OPPJ: Foreign investing involves special risks, such as risk of loss from currency fluctuation or political or economic uncertainty. The Fund focuses its investments in Japan, thereby increasing the impact of events and developments in Japan that can adversely affect performance. Derivative investments can be volatile and these investments may be less liquid than other securities, and more sensitive to the effect of varied economic conditions. As this Fund can have a high concentration in some issuers, the Fund can be adversely impacted by changes affecting those issuers. Due to the investment strategy of this Fund, it may make higher capital gain distributions than other ETFs. Dividends are not guaranteed, and a company currently paying dividends may cease paying dividends at any time. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index. The composition of the Index is governed by an Index Committee and the Index may not perform as intended.


Global Head of Research
Christopher Gannatti began at WisdomTree as a Research Analyst in December 2010, working directly with Jeremy Schwartz, CFA®, Director of Research. In January of 2014, he was promoted to Associate Director of Research where he was responsible to lead different groups of analysts and strategists within the broader Research team at WisdomTree. In February of 2018, Christopher was promoted to Head of Research, Europe, where he was based out of WisdomTree’s London office and was responsible for the full WisdomTree research effort within the European market, as well as supporting the UCITs platform globally. In November 2021, Christopher was promoted to Global Head of Research, now responsible for numerous communications on investment strategy globally, particularly in the thematic equity space. Christopher came to WisdomTree from Lord Abbett, where he worked for four and a half years as a Regional Consultant. He received his MBA in Quantitative Finance, Accounting, and Economics from NYU’s Stern School of Business in 2010, and he received his bachelor’s degree from Colgate University in Economics in 2006. Christopher is a holder of the Chartered Financial Analyst Designation.

Director, Macroeconomic Research
@AneekaGuptaWTAneeka Gupta is Director of Research at WisdomTree. Prior to the acquisition of ETF Securities in April 2018, Aneeka worked as an Equity & Commodities Strategist at the company. Aneeka has 17 years of experience working as a Research Analyst across a wide range of asset classes. In her current role she is responsible for conducting analysis for all in-house equity, commodity and macro publications and assisting the sales team with client queries around products and markets. Prior to WisdomTree, Aneeka began her career as an equity analyst at Bear Stearns International Ltd in London. She also worked as an Equity Sales Trader at Sunrise Brokers across US and Pan European Exchanges. Before that she worked as an Equity Derivatives Sales Manager at Mashreq Bank in Dubai. Aneeka holds a Masters in Mathematics from Oxford University and a BSc in Mathematics from the University of Delhi, India. She is also a CFA Charterholder.