QGRW
U.S. Quality Growth Fund

Published August 6, 2026

Global Head of Research
Markets don't hand out consistent winners. Equity leadership rotates, sometimes gradually, and sometimes without warning, between growth and value. For the past decade, the story was clear: U.S. large-cap growth, led by technology, dominated. The data in Figure 1 bears that out.1
But cycles can turn quickly, particularly over shorter periods. The opening weeks of 2026 showed value stepping forward, reversing a pattern that defined much of the last cycle. Then, we saw a growth resurgence, led by such areas defined as so-called ‘AI-Bottlenecks’, such as the memory stocks. Then, during much of June 2026, it appeared that the U.S. growth side of the ledger came back to earth.
Looking at Figure 1, with all that volatility, it is striking how close the S&P 500 Growth, Value and standard benchmark indices are through July 17, 2026.
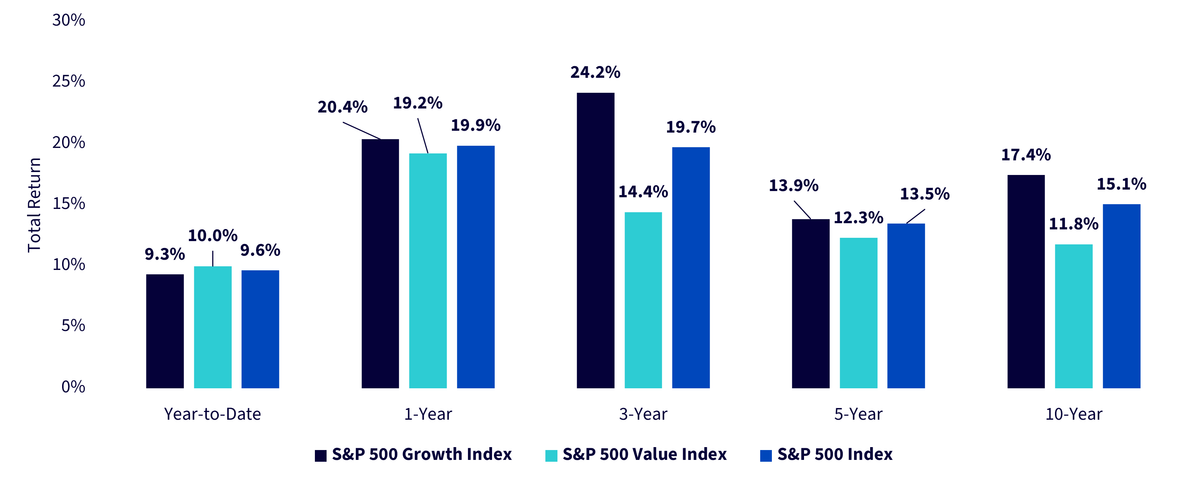
Sources: WisdomTree, FactSet, Morningstar, utilizing the WisdomTree Fund Compare Tool within the PATH suite of tools. Accessed on July 19, 2026, with return data as of July 17, 2026. Past performance is not indicative of future returns. You cannot invest directly in an index.
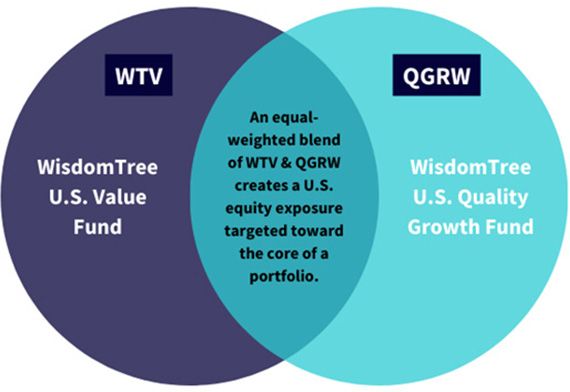
What if you didn’t have to pick a side? A well-constructed core allocation lets investors participate in both growth and value regimes, without constantly repositioning. Our 50/50 blend does exactly that, pairing two complementary WisdomTree strategies: one built around U.S. large-cap quality growth, the other around broad-based U.S. value.
The combination of these two strategies leads to a strong balance of sector exposures, attractive fundamental metrics, and, while limited, a solid performance history.
Source: WisdomTree.
The opening weeks of 2026 were a real test. Leadership in U.S. equities rotated sharply toward value, a notable reversal after years of growth dominance. And yet the 50/50 blend held its ground. Writing this piece in late July 2026, it appears that we have since seen a growth rally, led by the memory names, and then a growth correction. As Figure 3a shows, the WisdomTree 50/50 blend maintained an edge over the S&P 500 year-to-date, even as the environment exhibited this volatility of leadership.

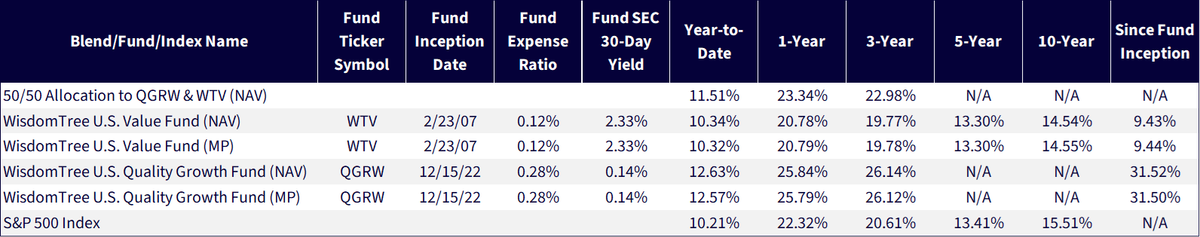
Sources: WisdomTree, Morningstar, FactSet specifically data from the Fund Comparison Tool in the PATH suite of tools, accessed July 19, 2026 with returns for Figure 3a as of July 17, 2026 and for Figure 3b as of June 30, 2026. NAV denotes total return performance at net asset value. MP denotes market price performance. In the case of WTV, the Fund’s objective changed effective December 18, 2017. Prior to December 18, 2017, Fund performance reflects the investment objective of the Fund when it tracked the performance, before fees and expenses, of the WisdomTree U.S. LargeCap Value Index. Past performance is not indicative of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance data quoted. For the most recent month-end and standardized performance and to download the respective Fund prospectuses, click the relevant ticker: QGRW, WTV.
Here’s what makes Figure 4 worth a close look: the 50/50 blend has delivered competitive returns while trading at a meaningful discount to the S&P 500 across notable valuation metrics, including estimated P/E, price-to-cash flow, price-to-book and price-to-sales. That’s not a small distinction. It suggests performance hasn’t been driven by multiple expansion alone, but by a genuine balance of earnings growth and valuation discipline. In an environment where leadership is shifting and valuations are under scrutiny, that combination matters.
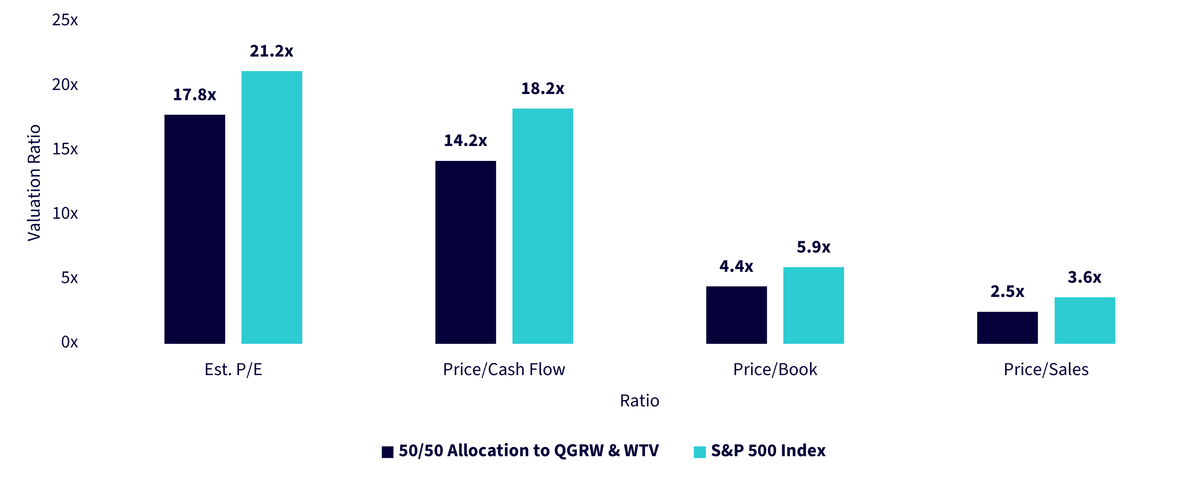
Sources: FactSet, Morningstar, WisdomTree, with data from WisdomTree’s Fund Compare Tool from WisdomTree’s PATH suite of tools. Figures as of June 30, 2026. Subject to change.
Markets in 2026 are forcing hard questions about concentration, valuation, and what “core” really means. The 50/50 allocation to QGRW and WTV is our answer: structural balance that doesn’t require predicting which style wins next. The year has already shown value surge ahead, then growth reassert itself, and we will keep watching as it unfolds. Either way, the blend has a component ready to respond. That’s what a true core holding should do.
1 “Growth” refers to the S&P 500 Growth Index, “Value” refers to the S&P 500 Value Index.
There are risks associated with investing, including possible loss of principal. Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
WTV: Value stocks, as a group, may be out of favor with the market and underperform growth stocks or the overall equity market. Funds focusing their investments on certain sectors increase their vulnerability to any single economic or regulatory development. This may result in greater share price volatility. While the Fund is actively managed, the Fund’s investment process is heavily dependent on quantitative models and the models may not perform as intended.
QGRW: Growth stocks, as a group, may be out of favor with the market and underperform value stocks or the overall equity market. Growth stocks are generally more sensitive to market movements than other types of stocks. The Fund is non-diversified, as a result, changes in the market value of a single security could cause greater fluctuations in the value of Fund shares than would occur in a diversified fund. The Fund invests in the securities included in, or representative of, its Index regardless of their investment merit and the Fund does not attempt to outperform its Index. The composition of the Index is governed by an Index Committee and the Index may not perform as intended.

Global Head of Research
Christopher Gannatti began at WisdomTree as a Research Analyst in December 2010, working directly with Jeremy Schwartz, CFA®, Director of Research. In January of 2014, he was promoted to Associate Director of Research where he was responsible to lead different groups of analysts and strategists within the broader Research team at WisdomTree. In February of 2018, Christopher was promoted to Head of Research, Europe, where he was based out of WisdomTree’s London office and was responsible for the full WisdomTree research effort within the European market, as well as supporting the UCITs platform globally. In November 2021, Christopher was promoted to Global Head of Research, now responsible for numerous communications on investment strategy globally, particularly in the thematic equity space. Christopher came to WisdomTree from Lord Abbett, where he worked for four and a half years as a Regional Consultant. He received his MBA in Quantitative Finance, Accounting, and Economics from NYU’s Stern School of Business in 2010, and he received his bachelor’s degree from Colgate University in Economics in 2006. Christopher is a holder of the Chartered Financial Analyst Designation.


