


The Federal Reserve (Fed) paused rate hikes in September, after having hiked in July (no policy meetings occur in August). However, the Federal Open Market Committee (FOMC) has adjusted its rate expectations for the upcoming year. Ten FOMC participants expect the Fed Fund target mid-point to be above 5% by the end of 2024. That compares with only six at the June meeting. the majority expected rates between 4.25-4.50% for end 2024, which is now the lowest anticipated range, with only two members aligning with it. This suggests the Fed is adopting a ‘higher for longer’ narrative.
While Fed Fund futures are pricing at the end of the hiking cycle, markets are recalibrating for a higher for longer scenario, and as a result, 10-year Treasury yields are spiking. At 4.47%, 10-year Treasury nominal yields are at their highest since 2007. Real yields at 2.11% are also the highest since 2008. That would normally place immense pressure on gold. Gold, however, is holding its own, with the yellow metal continuing to defy the historic real yield-gold relationships.
Figure 1: Gold vs real rates (Treasury Inflation-Protected Securities yield)
https://embed.chartblocks.com/1.0/?c=6512ae2e3ba0f6956811590b&t=0a15b3c7fc4940f
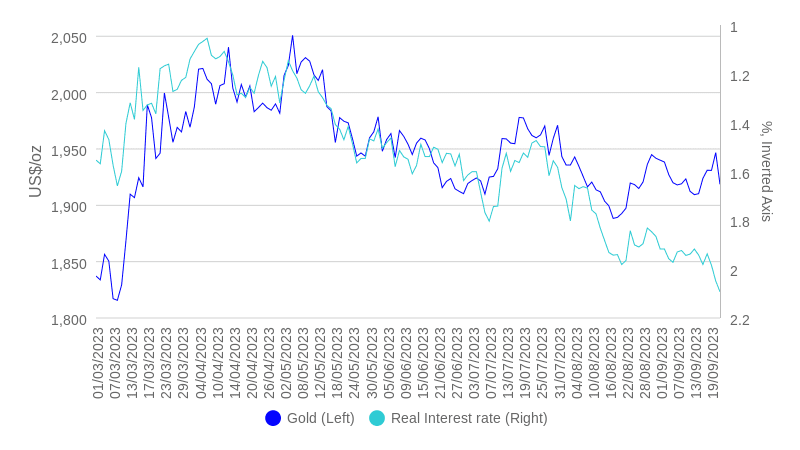
Source: Bloomberg, WisdomTree. 01/03/2023 – 22/09/2023. Historical performance is not an indication of future performance and any investments may go down in value.
Gold (in US Dollars) is also being flanked by an appreciating US Dollar. The US Dollar basket has appreciated by 5.8% between 13 July 2023 and 22 September 2023. Markets are also recalibrating where they think other central banks will end up. The Bank of England unexpectedly held rates in September and the European Central Bank’s September rate hike could be its last. A few months ago, markets were expecting these other central banks to continue to raise for longer. The interest rate differentials now support a stronger US Dollar, which is a headwind for gold. Once again gold appears to be dealing with this headwind very well.
Gold in other currencies is exhibiting considerably more strength. Gold in Yen is at an all-time high. Gold in Euros is only 2.9% below its all-time high reached in on 17 March 2023.
Figure 2: Gold and Dollar Basket
https://embed.chartblocks.com/1.0/?c=6512b6863ba0f6936c11590b&t=df28cb15de7a92e
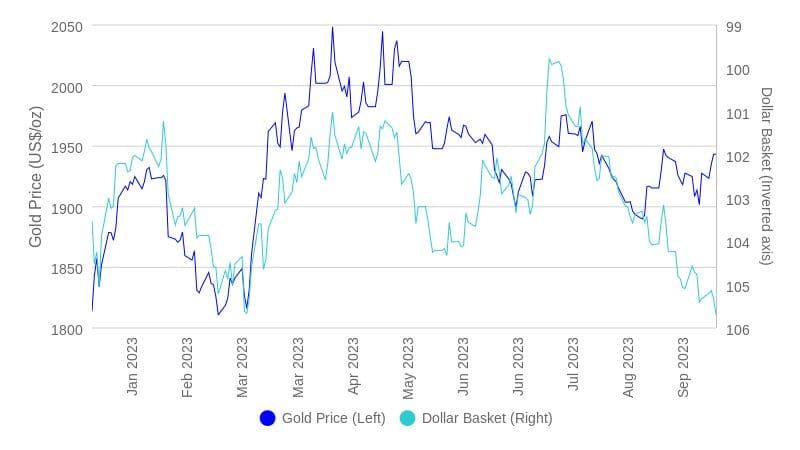
Source: Bloomberg, WisdomTree. 02/01/2023 – 22/09/2023. Historical performance is not an indication of future performance and any investments may go down in value.
Gold continued to see outflows from Exchange Traded Products (ETPs). That seems to reflect apathy towards physical gold from many institutional investors. In an environment of higher interest rates, some institutional investors are opting for gold futures exposure (due to the positive collateral yield embedded in futures prices). This trend explains why speculative positioning in gold futures remains around the long-term average.
Figure 3: Gold held in exchange-traded products
https://embed.chartblocks.com/1.0/?c=6512b94f3ba0f66e6d11590b&t=97d944a58873bec
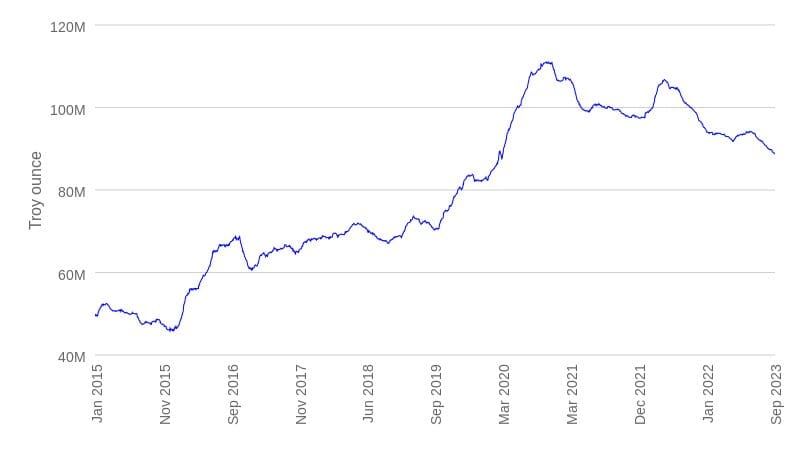
Source: Bloomberg, WisdomTree. 01/01/2015 – 22/08/2023. Historical performance is not an indication of future performance and any investments may go down in value.
Figure 4: Net speculative positioning in gold futures
https://embed.chartblocks.com/1.0/?c=6512d0503ba0f6427911590b&t=ffc61e6cc4acefe
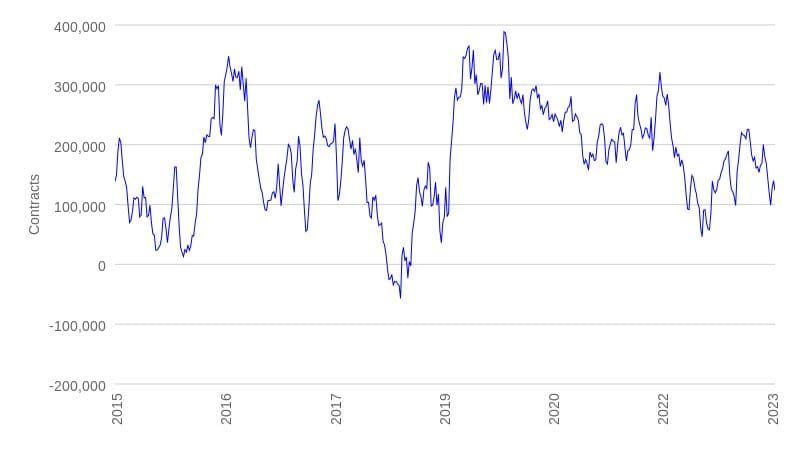
Source: Bloomberg, WisdomTree. 01/04/2015 – 22/08/2023. Historical performance is not an indication of future performance and any investments may go down in value.
Retail gold demand, however, remains strong. Especially in China, where the price premium over the institutional London market has risen to an all-time high. As the Chinese government stimulates the economy, we could see continued strength in Chinese demand. Given the large arbitrage, we are likely to see gold flow from London to China. According to the World Gold Council, Chinese gold ETPs saw inflows for three consecutive months – June, July and August - marking a clear divergence from international trends. In August 2023, Chinese ETP purchases were the highest since July 2022 amidst poor local equity performance and currency weakness.
Figure 5: Shanghai Gold Premium
https://embed.chartblocks.com/1.0/?c=6512eec33ba0f6030a11590b&t=4a84c980b5ee353
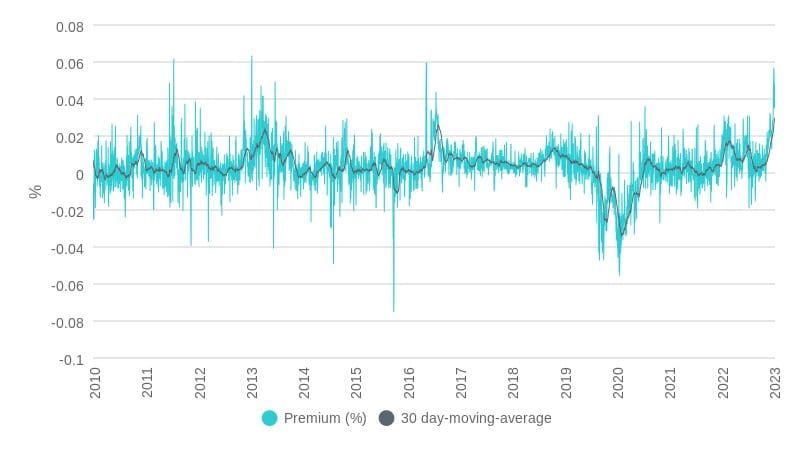
Source: WisdomTree, Bloomberg. February 2010 – September 2023. 30-day moving average. Historical performance is not an indication of future performance and any investments may go down in value.
In addition, the People’s Bank of China announced a purchase of 29 tonnes of gold in August, marking 10 consecutive months of gold buying. While many other central banks have not reported their August purchases yet, July data shows continued net buying. As we commented in earlier editions of this report, April and May data were aberrations due to Turkey’s central bank selling gold to meet local gold liquidity needs when gold imports were temporarily halted. Since those halts have been removed, Turkey’s central bank has resumed gold purchases, with 11 tonnes in June and a further 17 tonnes in July.
Figure 6: Central bank gold purchases
https://embed.chartblocks.com/1.0/?c=6512e3b23ba0f6770411590b&t=cac59de7e442eab
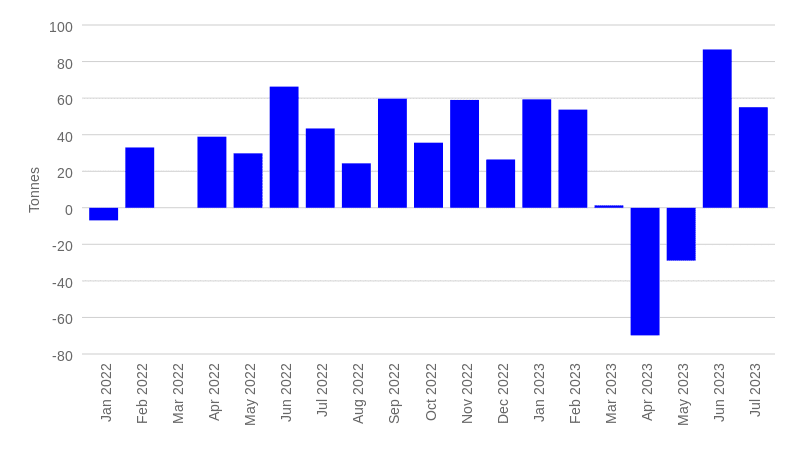
Source: International Monetary Fund, World Gold Council. January 2022 – July 2023. Historical performance is not an indication of future performance and any investments may go down in value.
Important Disclosure:
Past performance is not a reliable indicator of future performance. The price of gold does fluctuate and may be affected by numerous factors including supply and demand, the global financial markets and other political, financial, or economic events, which may negatively impact gold prices.
Categories
Perspectives in Onchain Finance
View all

About the contributor

Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe
@NiteshShahWTNitesh Shah is a seasoned financial professional with over 24 years of experience in research and investment strategy. As Head of Commodities & Macroeconomic Research at WisdomTree Europe, he leads market analysis and insights across asset classes, with a focus on commodities and exchange-traded products. Previously, he held roles at Moody’s, HSBC Investment Bank, The Pension Protection Fund, and Decision Economics, building expertise in market analysis and strategy. Nitesh earned a master’s degree in International Economics and Finance from Brandeis University and a bachelor's in Economics from the London School of Economics. His insights are frequently featured in financial media, and he is a sought-after speaker at industry events. He also hosts the ‘Commodity Exchange’ podcast, where he discusses trends shaping global markets. Passionate about guiding investors, Nitesh provides actionable insights to help them navigate complex financial landscapes.
Thought Leaders

Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe

Andrew Okrongly, CFA
Director, Model Portfolios

Blake Heimann
Associate Director, Quantitative Research

Christopher Gannatti, CFA
Global Head of Research

Chris Ryder
Head of WisdomTree Transfers

Dovile Silenskyte
Director, Digital Assets Research

Jason Guthrie
Director of Capital Markets, WisdomTree Europe

Jeff Weniger, CFA
Head of Equity Strategy

Jeremy J. Siegel
WisdomTree Senior Economist

Jeremy Schwartz, CFA
Global Chief Investment Officer

Kevin Flanagan
Head of Investment and Fixed Income Strategy

Mobeen Tahir
Director, Macroeconomics and Thematic Research

Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe

Pierre Debru
Head of Research, Europe

Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios

Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets

Samuel Rines
Macro Strategist, Model Portfolios

Vinh Tran
Associate Director, Business Development, Digital Assets

Will Peck
Head of WisdomTree Onchain

WisdomTree Onchain
Contributor
Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe
Andrew Okrongly, CFA
Director, Model Portfolios
Blake Heimann
Associate Director, Quantitative Research
Christopher Gannatti, CFA
Global Head of Research
Chris Ryder
Head of WisdomTree Transfers
Dovile Silenskyte
Director, Digital Assets Research
Jason Guthrie
Director of Capital Markets, WisdomTree Europe
Jeff Weniger, CFA
Head of Equity Strategy
Jeremy J. Siegel
WisdomTree Senior Economist
Jeremy Schwartz, CFA
Global Chief Investment Officer
Kevin Flanagan
Head of Investment and Fixed Income Strategy
Mobeen Tahir
Director, Macroeconomics and Thematic Research
Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe
Pierre Debru
Head of Research, Europe
Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios
Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets
Samuel Rines
Macro Strategist, Model Portfolios
Vinh Tran
Associate Director, Business Development, Digital Assets
Will Peck
Head of WisdomTree Onchain
WisdomTree Onchain
Contributor
Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe
Andrew Okrongly, CFA
Director, Model Portfolios
Blake Heimann
Associate Director, Quantitative Research
Christopher Gannatti, CFA
Global Head of Research
Chris Ryder
Head of WisdomTree Transfers
Dovile Silenskyte
Director, Digital Assets Research
Jason Guthrie
Director of Capital Markets, WisdomTree Europe
Jeff Weniger, CFA
Head of Equity Strategy
Jeremy J. Siegel
WisdomTree Senior Economist
Jeremy Schwartz, CFA
Global Chief Investment Officer
Kevin Flanagan
Head of Investment and Fixed Income Strategy
Mobeen Tahir
Director, Macroeconomics and Thematic Research
Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe
Pierre Debru
Head of Research, Europe
Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios
Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets
Samuel Rines
Macro Strategist, Model Portfolios
Vinh Tran
Associate Director, Business Development, Digital Assets
Will Peck
Head of WisdomTree Onchain
WisdomTree Onchain
Contributor