


Blake Heimann
Associate Director, Quantitative Research
Key Takeaways
- Rising government deficits and inflation concerns are reinforcing the long-term case for bitcoin as a non-sovereign store of value.
- Bitcoin miners offer levered upside with improving fundamentals, driven by high BTC prices, easing energy costs, and AI infrastructure repurposing.
- Stablecoins and real-world-asset tokenisation are gaining adoption, signalling blockchain’s growing role in global finance.
- Regulatory progress and capital market access are creating a more favourable environment for crypto-native companies.
- Blockchain equities combine macro-hedge potential with growth exposure to disruptive technologies reshaping the financial system.
Backdrop: debt, inflation and rising yields
The recent 90-day tariff pause with China gave risk assets a lift, and April CPI’s1 2.3% year-on-year (YoY) print signalled progress on inflation2. As a result, the outlook for near-term rate cuts from the Federal Reserve (Fed) pared back. Walmart’s earnings call contained warnings of pass-throughs of tariff costs to consumers, reminding markets that cost pressures may still be on the horizon.
Optimism around President Trump’s trip to the Middle East, securing $600 billion3 in defence and artificial intelligence (AI) commitments was met with Moody’s cut of the US credit rating from AAA to Aa1, citing continued problems with the budget deficit4. The most recent tax bill proposal puts the deficit on track to widen from 7% to 8% of GDP5,6. Ten-year Treasuries hovering near 5% now embed both rising credit and inflation risk, and foreign holders are quietly trimming exposure as currency volatility erodes real returns. In past debt-spiral regimes policymakers have chosen stealth default by letting inflation run; unsurprisingly, in an environment like this, capital is tilting toward scarce, non-sovereign stores of value.
Both gold and bitcoin sit near all-time highs, but bitcoin’s price action is more telling. It has broken correlation with US equities and is tracking gold’s scarcity bid7, but with the clarity of a fully capped supply, 24/7 liquidity, and censorship-resistant settlement. There is no central bank managing this currency, only code, and it appears as though more and more investors are beginning to trust this asset to serve as a long-term store of value.
Miners as high-beta bitcoin proxies
Public bitcoin miners convert cheap electricity into bitcoin inventory, and both sides of that equation are looking stronger than at any point since the 2024 halving8. With bitcoin trading above $100k on the back of growing government deficits, and energy costs easing amid rising OPEC output9 and US pro-energy policy, miners have a rare opportunity to expand margins. As of Q4 2024, the cost of production for publicly traded mining firms ranged from $25k to $80k per bitcoin10 (depending on energy mix, hardware efficiency, and scale), well below prevailing market prices. Also, many are repurposing any idle infrastructure for AI inferencing, unlocking an additional revenue stream powered by the same low-cost energy and compute11.
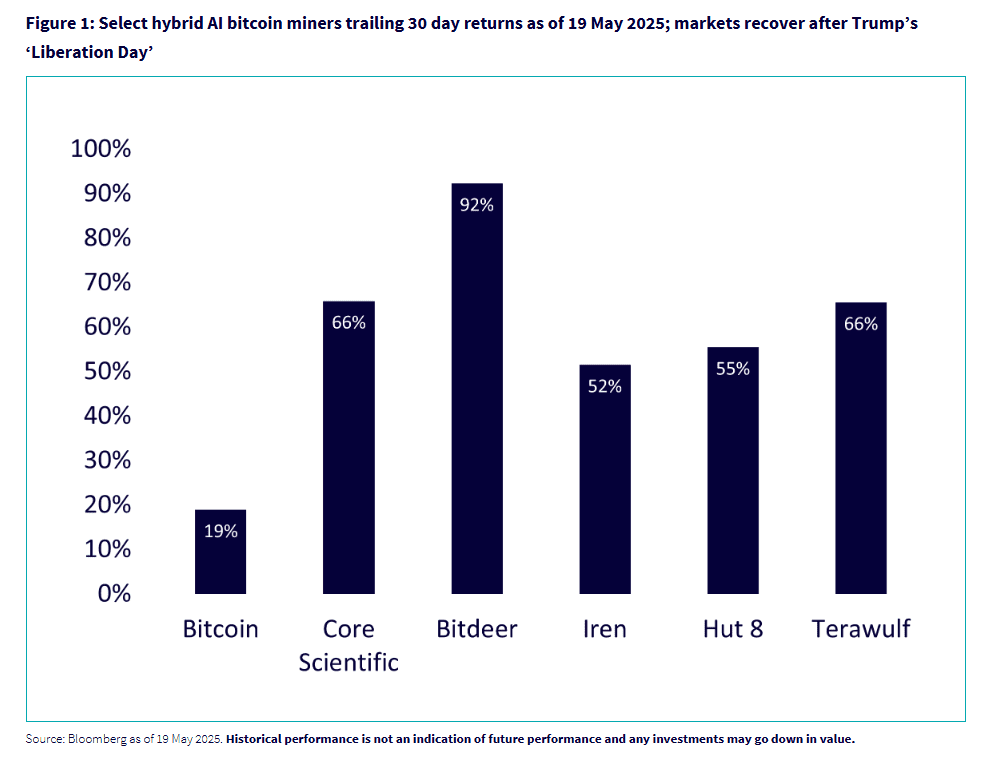
Market performance reflects these tailwinds: several miners are up over 50% in the last 30 days, outpacing bitcoin’s 20% return as markets recover from ‘Liberation Day’ tariff announcements. With bitcoin held on debt-financed balance sheets, these firms offer levered upside to further spot rallies, while diversified data centre strategies help cushion downside risks. In a potentially reflationary world facing monetary debasement, these firms resemble the high-beta gold miners of past commodity cycles—except their output is algorithmically scarce bitcoin.
Stablecoins, tokenisation, and the new rails of finance
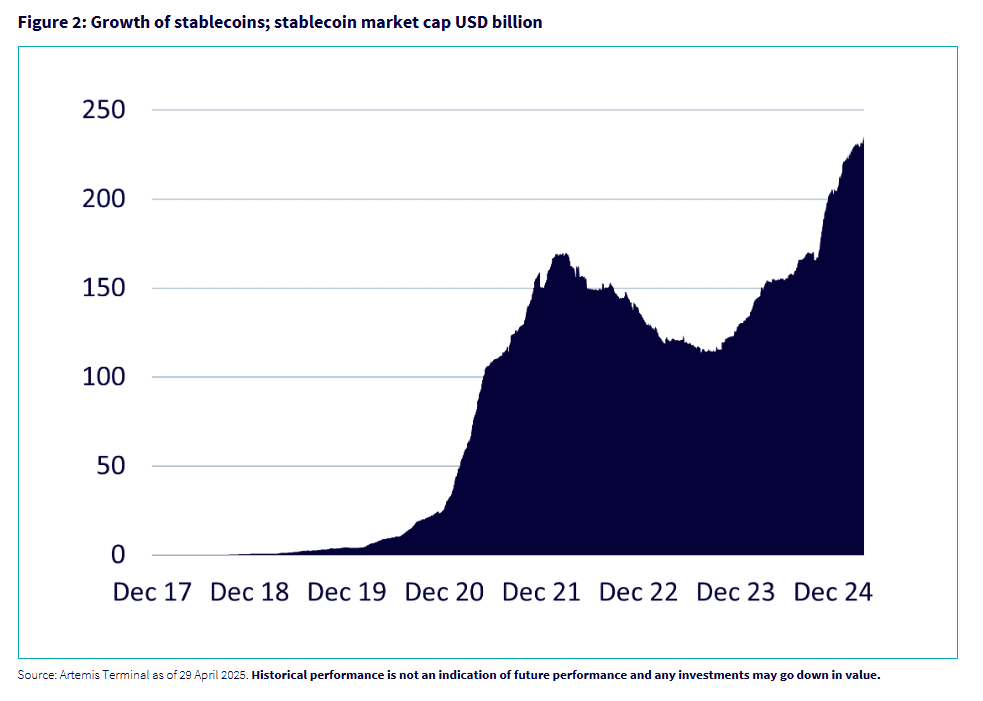
Stablecoins and tokenised assets are fast becoming the user-facing layer of the crypto economy. US dollar-pegged coins are quickly approaching $250 billion market cap and, in 2024, they moved $27.6 trillion in volume—more than Visa and Mastercard combined12.
Tether’s USDT dominates the field with $150 billion market cap, followed by Circle’s USDC with $60 billion, which is up over 80% in the last year13. Circle is eyeing an IPO with up to a $5 billion valuation14. PayPal’s own stablecoin hovers near $900 million in market cap, split across the Ethereum, Solana and Berachain blockchains15; and Stripe just bought Bridge to embed stable-coin settlement directly into its stack16. The incumbents are closely watching. Visa has unveiled its VTAP tokenisation platform, while Mastercard reports that roughly 30% of its 2024 transactions were tokenised17.
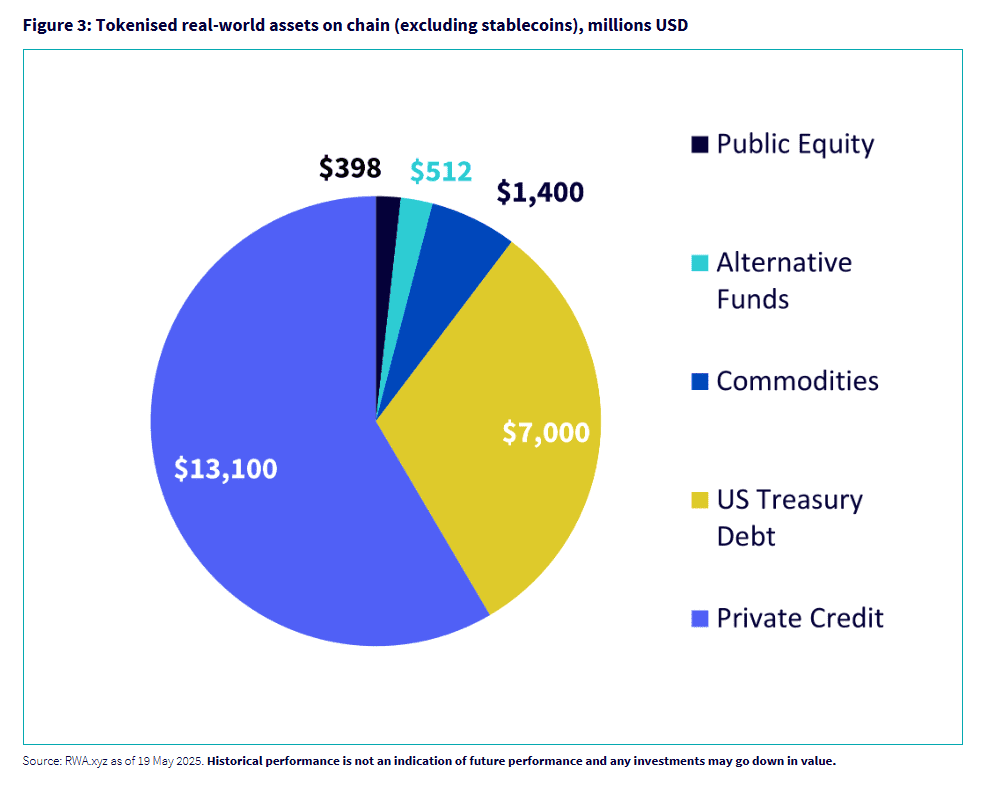
Real-world-asset (RWA) tokenisation is showing similar momentum. According to Rwa.xyz, the on-chain supply of tokenised treasuries, credit, and other assets has leapt from about $5 billion at the start of 2023 to more than $20 billion today18. Broadridge’s distributed-ledger repo platform alone already clears $1 trillion per month in tokenised collateral19. By shifting settlement and record-keeping to smart contracts (code running on the blockchain), firms can automate middle- and back-office work that requires layers of manual reconciliation. The result is lower costs, faster settlement, and broader accessibility, with the added benefits of 24/7 liquidity.
The opportunity is large enough that even big tech wants in. It has been reported that Meta is re-engaging its efforts for stablecoin integration, with aims to let its billions of users send low-cost, cross-border payments in-app20. If that happens, the rails of finance may soon look very different from the ones we’ve known.
Policy tailwinds
SEC Commissioner Hester Peirce has revived her ‘Safe Harbor 2.0’ blueprint, which would give new token networks a three-year grace period from many securities-law obligations as long as they publish semi-annual updates and an ‘exit report’ at network maturity21. The goal is to let projects prove themselves before regulators decide whether their tokens behave like equity, commodities, or something entirely new. That breathing-room could finally allow developers and investors to explore the equity-like side of crypto assets, including real-world cash-flow rights. A case in point is decentralised exchange Uniswap: trading fees already flow into the protocol’s on-chain treasury and could one day be paid to UNI token holders, much like dividends.
Capital-market acceptance
Wall Street is catching up fast. Recently dropped SEC lawsuits have opened the door to broader market activity. Coinbase, now in the S&P 500, is acquiring crypto derivatives exchange Deribit for $2.9 billion22, offering a sign that crypto-native mergers and acquisitions are accelerating. Robinhood is expanding into Canada with a $179 million acquisition of WonderFi, whose portfolio spans payments, crypto staking, wallets, and its own Ethereum L2. Public markets are also continuing to open up to crypto firms. Galaxy Digital has completed its long-awaited Nasdaq ‘uplisting’ from the Toronto Stock Exchange. eToro’s recent IPO23 success saw prices rise 34% on its market debut, achieving a $5.6 billion valuation24. And still, markets await high profile IPOs such as Kraken and Circle. Institutional wrappers for direct crypto access tell the same story: spot bitcoin and multi-asset crypto exchange-traded funds (ETFs) and exchange-traded products (ETPs) now hold more than $100 billion in assets25.
Conclusion
The financial system is quietly being rewired. Growing deficits, sticky inflation, and 5% Treasury yields have investors hunting for assets that can’t be printed away. Adoption of bitcoin as an alternative store of value is growing. With bitcoin-heavy balance sheets and margins expanding, miners stand to benefit. At the same time, stablecoins are beginning to rival traditional payment rails, and real-world assets are migrating to blockchains that settle 24/7. The signs are hard to ignore. Regulation is finally bending toward clarity, and the doors to the traditional capital markets are opening. The convergence between traditional financial system and the crypto financial system is underway.
Sources:
1 CPI = Consumer price index.
2 United States Inflation Rate
3 Trump says US to lift Syria sanctions, secures $600 billion Saudi deal | Reuters
4 U.S. Loses Last Triple-A Credit Rating - WSJ
5 GDP = Gross domestic product.
6 How Trump’s ‘Big, Beautiful Bill’ Could Spoil the Stock Market Party - Barron's
7 https://www.cnbc.com/2025/04/22/crypto-market-today.html
8 Bitcoin Halving and Mining Update: Mid-2024 Perspective
9 Opec+ calls time on attempts to boost oil price as Trump visit looms
10 TheMinerMag
11 Bitcoin Miners Powering the AI Revolution | Galaxy
12 Stablecoin volumes surpassed Visa and Mastercard combined in 2024
13 Top Stablecoins by Market Cap | Messari
14 Circle Eyes $5 Billion Valuation For Upcoming Initial Public Offering
15 PayPal USD: Circulating and stats - DefiLlama
16 Stripe closes $1.1 billion Bridge deal, prepares for stablecoin push
17 Mastercard 10-K Filing 2025
18 RWA.xyz | Analytics on Tokenized Real-World Assets
19 DLR Transacts $1 Trillion a Month | Broadridge
20 Meta Considering Using Stablecoins for Cross-Border Payments
21 SEC.gov | Token Safe Harbor Proposal 2.0
22 Coinbase to Acquire Deribit: Becoming the Most Comprehensive Global Crypto Derivatives Platform
23 IPO = initial public offering.
24 Israel's eToro valued at $5.6 billion in bumper Nasdaq debut after tariff-driven delays | Reuters
25 Source: Bloomberg
Perspectives in Onchain Finance
View all

About the contributor

Blake Heimann
Associate Director, Quantitative Research
Blake Heimann joined WisdomTree in 2020 and supports the creation, maintenance, and reconstitution of WisdomTree’s indices. Blake began his career in finance in 2017 as an Analyst at TD Ameritrade and, later, a Quantitative Analyst with a focus on the development of machine learning applications in finance.
Blake has bachelor’s degrees in Mathematics and Economics from Iowa State University, as well as a master’s in Computer Science from Georgia Tech, with a specialisation in Machine Learning. He is currently pursuing a master’s in Finance from the London School of Economics
Thought Leaders

Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe

Andrew Okrongly, CFA
Director, Model Portfolios

Blake Heimann
Associate Director, Quantitative Research

Christopher Gannatti, CFA
Global Head of Research

Chris Ryder
Head of WisdomTree Transfers

Dovile Silenskyte
Director, Digital Assets Research

Jason Guthrie
Director of Capital Markets, WisdomTree Europe

Jeff Weniger, CFA
Head of Equity Strategy

Jeremy J. Siegel
WisdomTree Senior Economist

Jeremy Schwartz, CFA
Global Chief Investment Officer

Kevin Flanagan
Head of Investment and Fixed Income Strategy

Mobeen Tahir
Director, Macroeconomics and Thematic Research

Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe

Pierre Debru
Head of Research, Europe

Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios

Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets

Samuel Rines
Macro Strategist, Model Portfolios

Vinh Tran
Associate Director, Business Development, Digital Assets

Will Peck
Head of WisdomTree Onchain

WisdomTree Onchain
Contributor
Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe
Andrew Okrongly, CFA
Director, Model Portfolios
Blake Heimann
Associate Director, Quantitative Research
Christopher Gannatti, CFA
Global Head of Research
Chris Ryder
Head of WisdomTree Transfers
Dovile Silenskyte
Director, Digital Assets Research
Jason Guthrie
Director of Capital Markets, WisdomTree Europe
Jeff Weniger, CFA
Head of Equity Strategy
Jeremy J. Siegel
WisdomTree Senior Economist
Jeremy Schwartz, CFA
Global Chief Investment Officer
Kevin Flanagan
Head of Investment and Fixed Income Strategy
Mobeen Tahir
Director, Macroeconomics and Thematic Research
Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe
Pierre Debru
Head of Research, Europe
Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios
Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets
Samuel Rines
Macro Strategist, Model Portfolios
Vinh Tran
Associate Director, Business Development, Digital Assets
Will Peck
Head of WisdomTree Onchain
WisdomTree Onchain
Contributor
Alice Liu
Senior Associate, Cryptocurrency Investments, WisdomTree Europe
Andrew Okrongly, CFA
Director, Model Portfolios
Blake Heimann
Associate Director, Quantitative Research
Christopher Gannatti, CFA
Global Head of Research
Chris Ryder
Head of WisdomTree Transfers
Dovile Silenskyte
Director, Digital Assets Research
Jason Guthrie
Director of Capital Markets, WisdomTree Europe
Jeff Weniger, CFA
Head of Equity Strategy
Jeremy J. Siegel
WisdomTree Senior Economist
Jeremy Schwartz, CFA
Global Chief Investment Officer
Kevin Flanagan
Head of Investment and Fixed Income Strategy
Mobeen Tahir
Director, Macroeconomics and Thematic Research
Nitesh Shah
Head of Commodities and Macroeconomic Research, WisdomTree Europe
Pierre Debru
Head of Research, Europe
Rick Harper
Chief Investment Officer, Fixed Income and Model Portfolios
Rohan Ranadive
Chief Risk Officer, WisdomTree Digital Assets
Samuel Rines
Macro Strategist, Model Portfolios
Vinh Tran
Associate Director, Business Development, Digital Assets
Will Peck
Head of WisdomTree Onchain
WisdomTree Onchain
Contributor