GDE
Efficient Gold Plus Equity Strategy Fund

Published September 24, 2026

Global Head of Research
For decades, portfolio construction has revolved around a simple constraint: investors have 100 percent of a total allocation, and every new addition requires taking a portion from somewhere else. That constraint has shaped portfolio construction, as reflected in the dominance of 60/40 portfolios and the difficulty of incorporating alternatives without sacrificing expected return.
WisdomTree’s Efficient Capital Framework was not introduced as a theoretical concept—it was launched into the market in 2018 with the debut of the WisdomTree U.S. Efficient Core Fund (NTSX).
NTSX represented the practical implementation of an idea that had largely lived in institutional portfolios and academic journals for decades. By combining a 90% allocation to U.S. equities with a 60% exposure to U.S. Treasury futures, the strategy delivered approximately 150% notional exposure, effectively recreating a traditional 60/40 portfolio, but doing so more efficiently, using less capital for the same overall notional exposure.
The innovation wasn’t leverage for its own sake. It was about solving a structural inefficiency in portfolio construction, thereby freeing up capital without giving up core exposures.
Since 2018, WisdomTree has expanded its range of options within the broader Efficient Capital Framework, and we think gold offers one of the most illustrative examples of helping investors solve a classic portfolio conundrum.
One of the most intuitive uses of newly created portfolio “space” is gold, an asset that has served as a store of value for centuries, yet remains persistently debated in modern portfolio construction.
Unlike equities or bonds, gold does not generate cash flows. It pays no dividends, earns no interest and compounds nothing. In 2011, Warren Buffett famously stated “Today the world’s gold stock is about 170,000 metric tons. If all of this gold were melded together, it would form a cube of about 68 feet per side… You can fondle the cube, but it will not respond.”1 That critique is valid, but it could also be incomplete. Gold’s role has never been about income. It is about diversification, purchasing power preservation and resilience in extreme environments.
Gold’s role in portfolios is often described in static terms, including:2
But in practice, its value is far more dynamic.
Gold tends to assert itself during periods when traditional assets face pressure, not only because of correlation properties, but because of how markets actually function under stress. 2026 offered a clean illustration. Gold surged to a record above $5,590/oz on January 28, driven by geopolitical anxiety and mounting questions about Federal Reserve independence, before staging one of its sharpest reversals in decades.3
What’s often overlooked is the mechanism, and this year showed it plainly. Within days of that record, gold fell nearly 10% in a single session as a crypto-led deleveraging cycle spilled into precious metals: traders facing margin calls after unwinding bitcoin and equity positions sold gold and silver simply because they were liquid enough to raise cash quickly, and exchange margin hikes compounded the slide.4 A similar pattern repeated in March, when a hotter-than-expected inflation print pushed the Fed toward a “higher for longer” stance, the dollar surged, equities sold off, and gold fell alongside them as leveraged funds again reached for their most liquid holdings to meet calls. In neither case had gold’s underlying role changed; the selling reflected forced liquidity mechanics rather than a verdict on the metal’s fundamentals. In the months that followed, as those technical pressures worked through the system, gold’s underlying drivers reasserted themselves, and by August a softening labor market alongside a Fed seen as unable to satisfy both sides of its mandate revived the bid.
At the same time, gold’s 2026 path stayed tied to macro conditions in ways consistent with its historical drivers. Real interest rate expectations, dollar strength, and the credibility of the Fed’s reaction function each showed up directly in the price. Gold cheapened when rate cut odds faded and the dollar firmed, and it firmed again when the market began pricing stagflation risk, questioning whether the Fed could contain inflation without further damaging employment. In an environment marked by elevated fiscal deficits and recurring doubts about monetary policy independence, gold’s role became more pronounced, not as a return generator in the traditional sense, but as a portfolio stabilizer with potential asymmetric upside in stress scenarios.5
In that context, gold’s lack of yield is not a flaw, and it is what allows it to behave differently when it matters most.
Still, the implementation challenge remains.
Allocating to gold traditionally requires selling something else in a portfolio, usually equities—the very asset class that has historically driven long-term wealth creation. This creates a difficult trade-off: diversification versus compounding.
This is where WisdomTree’s Efficient Gold Plus Equity Strategy Fund (GDE) fits within the Efficient Capital Framework. This strategy was launched by WisdomTree in March 2022.
GDE is designed to resolve that tension by combining approximately 90% exposure to U.S. equities6 with 90% exposure to gold futures, delivering roughly 180% notional exposure. Instead of replacing equities with gold, it allows investors to hold both simultaneously.
In effect, if Efficient Core creates space, GDE fills it with a complementary asset, one that behaves differently across market regimes, without forcing investors to give up their primary engine of growth.
The result is a more balanced portfolio: one that can participate in upside, but is also better equipped for the environments where traditional allocations fall short.
To make this more tangible, we can compare three portfolio allocations, but first we have to define our different ETF building blocks.
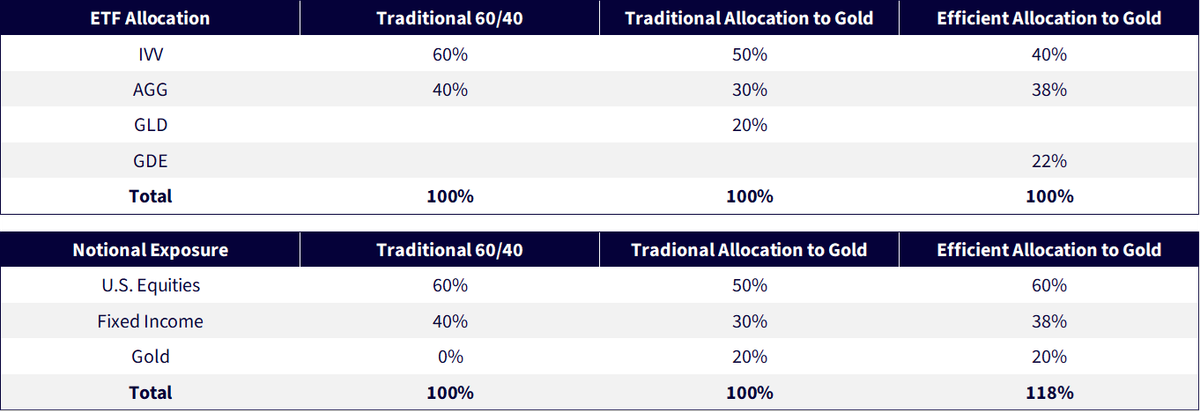
In Figure 1, the starting point is the ‘traditional 60/40’, 60% equities (IVV) and 40% fixed income (AGG). This serves as a familiar baseline, with 100% total notional exposure split between stocks and bonds.
From there, the ‘traditional allocation to gold’ approach, which introduces exposure to gold by reallocating capital: 50% equities, 30% bonds and 20% gold, in this case through GLD. This maintains 100% total exposure but requires reducing core equity and bond allocations to make room for the diversifier, in this case, gold.
The ‘Efficient Allocation to Gold’ takes a different path.
Overall, the idea is to keep the roughly 60% U.S. equities and 40% U.S. fixed income parts of the allocation intact, but to then add exposure to gold over the top. Figure 1 shows how placing:
This leads to notional exposures of 60% U.S. equities, 38% U.S. fixed income and 20% gold, in this case, gold futures.
This is the key distinction. The investor keeps close to the original allocation and adds a potential diversifier, in this case gold, over the top.
Figure 1: Gold Without the Trade-Off: Rethinking Portfolio Construction
Has It Worked? The Performance Case for Efficient Gold
Figure 2a reflects gold’s own 2026 arc as much as it does a clean performance hierarchy. The one-month result is a direct read on August’s strength, a rally that lifted both gold allocations well clear of 60/40. The three-month figure tells a more mixed story, since a softer July sits alongside that August rebound, temporarily narrowing the gap. Year-to-date returns still carry the drag from gold’s pullback off its January record high, which is why the gold allocations’ edge over 60/40 looks more modest here than elsewhere on the chart. Extend the window to one-year and three-year, however, and the picture changes, as both spans capture the full run-up into that January peak, and the lead of efficient allocation to gold over 60/40 widens accordingly, with traditional allocation close behind. We do recognize that gold has delivered strong performance over this period, which is really defined by GDE’s inception date of March 17, 2022.
Figure 2a: Adding Gold Without Sacrificing Returns: The Performance Evidence
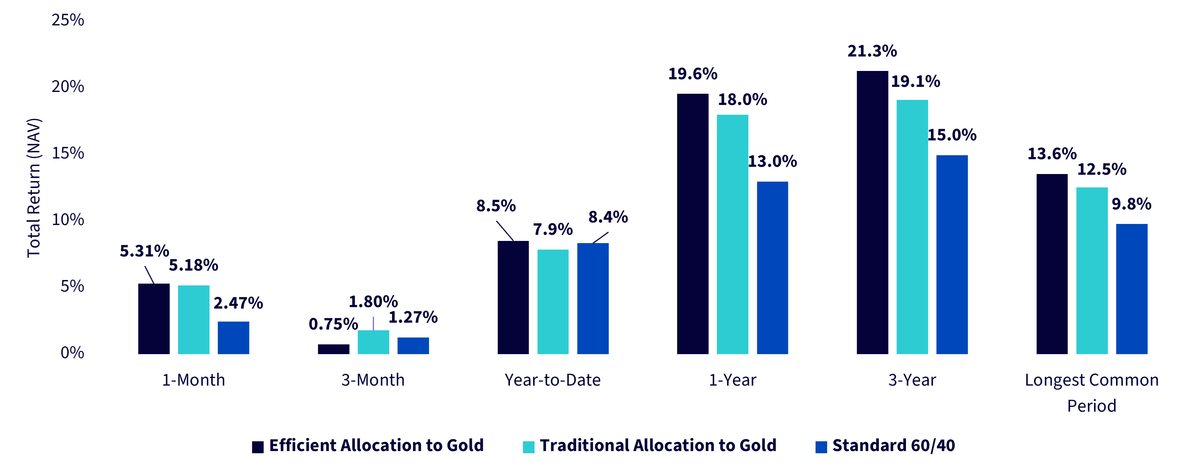
Figure 2b: Standardized Returns
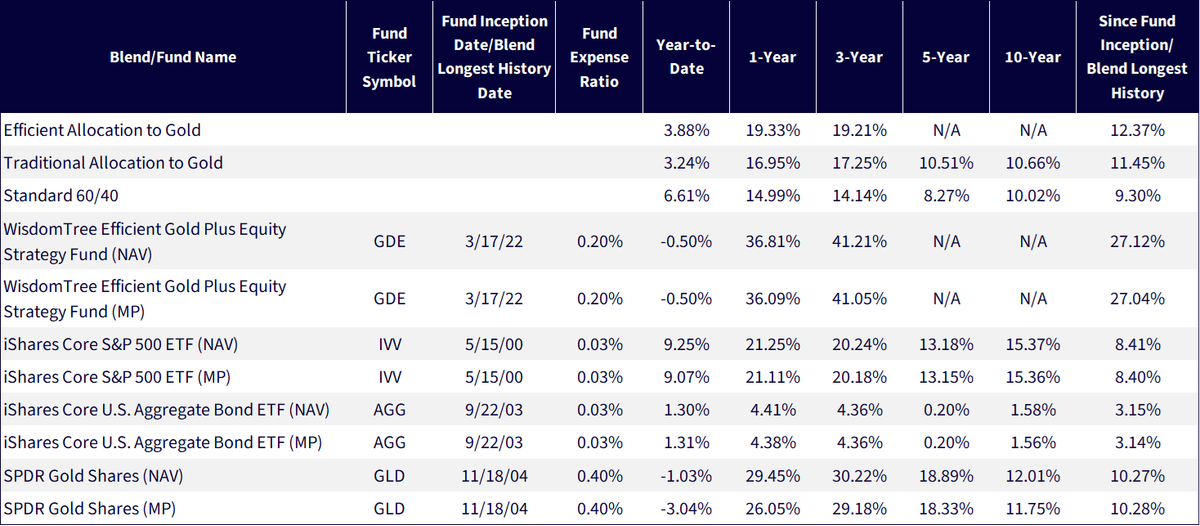
Sources: Morningstar, FactSet and WisdomTree, specifically, data are from the PATH Fund Comparison Tool, accessed August 30, 2026, but showing returns for the period ended August 28, 2026 for Figure 2a and June 30, 2026 for Figure 2b. Past performance is not indicative of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance data quoted. For the most recent month-end and standardized performance and to download the respective Fund prospectuses, click the relevant ticker: GDE, IVV, AGG, GLD.
Gold has always occupied a unique place in portfolios, valued for its resilience, yet often underutilized because of the trade-offs required to own it. For decades, investors have faced a binary choice: allocate to gold and give up a certain percentage exposure to equities, or prioritize growth and forgo diversification.
Efficient Capital changes that equation.
By separating exposure from capital, strategies like GDE allow investors to move beyond that trade-off. Instead of asking whether to own gold or equities, the question becomes how to own both in a more intentional way. The result is a portfolio that retains its core growth engine while incorporating an asset designed to respond differently across macro environments.
In a world shaped by shifting geopolitical risks, evolving monetary policy and less reliable traditional diversification, that flexibility matters. The goal is no longer just participation; it is adaptability.
And that may ultimately be the most valuable asset of all.
Figure 3: Additional Information
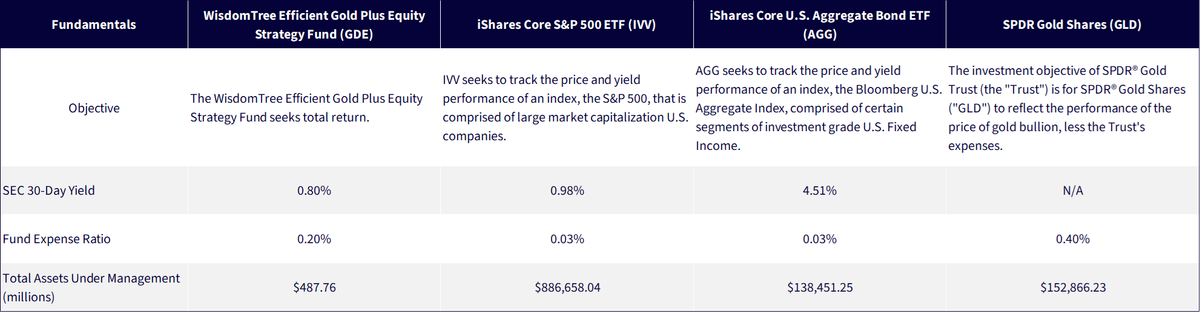
Sources: Respective fund webpages for each ETF sponsor. Assets under management data is as of August 28, 2026. Subject to change.
1Source: Buffett, W. E. (2011). Berkshire Hathaway Inc. 2011 annual letter to shareholders. Berkshire Hathaway Inc.
2Source: Baur, D. G., & McDermott, T. K. (2025). Revisiting the hedging and safe haven roles of gold. Journal of International Financial Markets, Institutions and Money.
3Source: U.S. News & World Report. (2026, February 1). Gold, silver extend fall as CME margin hikes compound sharp selloff. Reuters.
4Source: Zestlab. (2026, April 9). Gold crashes 3% to $4,830 in 2026 margin call shock.
5Source: Franck, T. (2026, August 12). Where gold price is headed next as Fed rate hike and inflation odds change direction. CNBC.
6U.S. equities in the context of GDE refers to 500 U.S. large market capitalization stocks that are weighted on the basis of market capitalization.
All funds are managed differently and do not react the same way to economic or market events. The investment objectives, strategies, policies or restrictions of other funds may differ and more information can be found in their respective prospectuses. Therefore, we generally do not believe it is possible to make direct fund-to-fund comparisons in an effort to highlight the benefits of a fund versus another similarly managed fund.
There are risks associated with investing, including possible loss of principal.
GDE: The Fund is actively managed and invests in U.S.-listed gold futures and U.S. equity securities. The Fund’s use of U.S. listed gold futures contracts will give rise to leverage, magnifying gains and losses and causing the Fund to be more volatile than if it had not been leveraged. Moreover, the price movements in gold and gold futures contracts may fluctuate quickly and dramatically, and have a historically low correlation with the returns of the stock and bond markets. While the Fund is actively managed, the Fund’s investment process is heavily dependent on quantitative models and the models may not perform as intended.
NTSX: While the Fund is actively managed, the Fund’s investment process is heavily dependent on quantitative models and the models may not perform as intended. The Fund invests in derivatives to gain exposure to U.S. Treasuries. The return on a derivative instrument may not correlate with the return of its underlying reference asset. The Fund’s use of derivatives will give rise to leverage and derivatives can be volatile and may be less liquid than other securities. As a result, the value of an investment in the Fund may change quickly and without warning and you may lose money. Interest rate risk is the risk that fixed income securities, and financial instruments related to fixed income securities, will decline in value because of an increase in interest rates and changes to other factors, such as perception of an issuer’s creditworthiness.
Please read the Fund’s prospectus for specific details regarding the Fund’s risk profile.
For additional fund disclosures, click the respective ticker: IVV, AGG, GLD.

Global Head of Research
Christopher Gannatti began at WisdomTree as a Research Analyst in December 2010, working directly with Jeremy Schwartz, CFA®, Director of Research. In January of 2014, he was promoted to Associate Director of Research where he was responsible to lead different groups of analysts and strategists within the broader Research team at WisdomTree. In February of 2018, Christopher was promoted to Head of Research, Europe, where he was based out of WisdomTree’s London office and was responsible for the full WisdomTree research effort within the European market, as well as supporting the UCITs platform globally. In November 2021, Christopher was promoted to Global Head of Research, now responsible for numerous communications on investment strategy globally, particularly in the thematic equity space. Christopher came to WisdomTree from Lord Abbett, where he worked for four and a half years as a Regional Consultant. He received his MBA in Quantitative Finance, Accounting, and Economics from NYU’s Stern School of Business in 2010, and he received his bachelor’s degree from Colgate University in Economics in 2006. Christopher is a holder of the Chartered Financial Analyst Designation.

