3BALWisdomTree EURO STOXX Banks 3x Daily Leveraged
ISIN: IE00BLS09N400,89%
Management Fee (MER)
As of 29/10/2026
8 December 2014
Inception Date
160.426.594 US$
Fund AUM
As of 29/10/2026
EUR
Base currency
Overview
Product Description
WisdomTree EURO STOXX Banks 3x Daily Leveraged is a fully collateralised, UCITS eligible Exchange Traded Product (ETP) designed to provide investors with a leveraged exposure to the EURO STOXX Banks. The ETP tracks the EURO STOXX Banks Daily Leverage 3 EUR Net Return Index (SX7T3L), providing a total return comprised of 3 times the daily performance of the EURO STOXX® Banks Net Return Index, adjusted to reflect fees and costs inherent to maintaining a leveraged position in stocks. For example, if the EURO STOXX® Banks Net Return Index rises by 1% over a day, then the ETP will rise by 3%, excluding fees. However if the EURO STOXX® Banks Net Return Index falls by 1% over a day, then the ETP will fall by 3%, excluding fees.
Why 3BAL?
- Gain a leveraged exposure to the performance of EURO STOXX Banks.
- Magnify your returns in one simple trade.
- UCITS eligible and fully collateralised.
- Transparent performance and fees.
- Easy to invest: Everything in one product which does not require the investor to manage futures, borrow cash or short stocks.
- Risk Management: You cannot lose more than the amount invested.
- Liquidity: Trades on exchange, with multiple authorised participants (APs) and market makers (MMs).
Potential Risks
- An investment in an ETP involves a degree of risk. Any decision to invest should be based on the information contained in the relevant prospectus. Prospective investors should obtain independent accounting, tax and legal advice and should consult their professional advisers to ascertain the suitability of this ETP as an investment to their own circumstances.
- This ETP is structured as a debt security and not as shares (equity) and can be created and redeemed on demand by authorised participants and traded on exchange just like shares in a company. This ETP is not a UCITS product.
- Investing in Short and Leveraged ETPs is only suitable for sophisticated and or informed investors who understand leverage, daily rebalancing and compounded daily returns and are willing to magnify potential losses. Short and Leveraged ETPs are only intended for investors who understand the risks involved in investing in an ETP with short or leveraged exposure and who intend to invest on a short term basis. Any investment in a short or leveraged ETP should be monitored on a daily basis to ensure consistency with your investment strategy. You should understand that investments in daily leveraged ETPs held for a period of longer than the recommended holding period of one day, may not provide returns equivalent to the return from the relevant unleveraged investment multiplied by the relevant leverage factor over the same period. Daily compounding may result in returns which an investor may not expect, if the investor has not fully understood how a daily leveraged ETP works. Potential losses in leveraged ETPs may be magnified in comparison to investments that do not incorporate leverage. In extreme volatility, returns of leveraged ETPs, even over one day, may under-perform the return of the underlying unleveraged index multiplied by the ETP’s leverage factor because of protection mechanisms within the ETP structure, intended to protect against intra-day market crashes. For more information see here.
- Market Risk: The value of securities in this ETP is directly affected by increases and decreases in the value of the Index. Accordingly, the value of a security may go up or down and a security holder may lose some or all of the amount invested but can not lose more than the amount invested.
- Liquidity risk: There can be no certainty that securities can always be bought or sold on a stock exchange or that the market price at which the securities may be traded on a stock exchange will always accurately reflect the performance of the Index.
- Currency Risk: The price of securities in this ETP is generally quoted in EUR. To the extent that a security holder purchases securities in another currency, the value will be affected by changes in the exchange rate.
- Counterparty risk: The Issuer is reliant on there being swap counterparties available to enter into swap agreements on a continuing basis and, if no swap counterparties are willing to do so, the ETP will not be able to achieve its investment policy of tracking the performance of the Index.
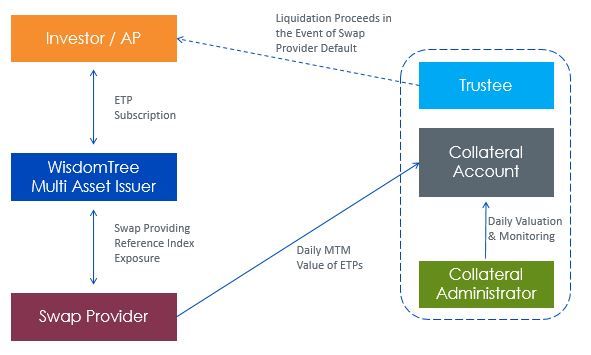
- Credit Risk: The Issuer is subject to the risk that third party service providers may fail to return property or collateral belonging to the Issuer or pay money due to the issuer. The ETP is backed by swaps. The payment obligations of the swap counterparties to the Issuer are protected by collateral held which is marked to market daily. The collateral is held in segregated accounts at The Bank of New York Mellon. In the event a swap counterparty defaults, the proceeds from realisation of the collateral may be less than what the investor expects. Details of the collateral held can be found in the Collateral section of the WisdomTree website (www. Wisdomtree. Com).
- Please see the risks factors section of the Prospectus for a more detailed discussion of the potential risks
Articles and Research Papers


Mobeen Tahir
What’s Hot: An attractive entry point for investing in nuclear energy
Nuclear stocks have slipped this year, yet Amazon and Google are signing 20-year power deals, 39 countries are backing a tripling of capacity and long-term uranium prices are at record highs. So why have the shares fallen? In this blog post, we look at who has pulled back and why, and what it could mean for investors waiting for an entry point.
- Energy Transition
- Equities
- Megatrends


Aneeka Gupta
Rethinking emerging markets: the case for excluding state-owned enterprises
Emerging markets have delivered faster economic growth than the developed world, yet equity returns have lagged. Weak governance and state ownership are central reasons, diverting value away from minority shareholders and exposing investors to regulatory shocks. We examine why growth fails to reach shareholders and how an ex-State-Owned Enterprises approach offers a more efficient way to own the asset class.
- Emerging Markets
- Equities

Aneeka Gupta
Past the AI Trade: Japan's broadening earnings and compounding reforms
Japan's policy rate rose to a multi-decade high, yet the yen stayed weak as a more hawkish Federal Reserve kept the dollar firm. The familiar link between the rate differential and the currency has broken down. Meanwhile, corporate governance reform keeps compounding. Payout ratios now rival the US and Europe, and earnings are broadening beyond AI into machinery and banks, supporting exporter-tilted dividend paying Japanese equities.
- AI
- Equities
- Japan
- US

Aneeka Gupta
High dividend investing in an era of persistent inflation
High dividend equities can strengthen portfolio income, but headline yield alone is a poor guide. Global payouts are growing faster than inflation, while sector and regional contributions vary widely. WisdomTree’s systematic approach combines yield, quality, momentum and dividend weighting to target durable income while seeking to reduce exposure to potential yield traps.
- High Dividend
- Equities
- Europe / Eurozone
- Fixed Income
- US
Fund Overview
Product Overview | As of 29/10/2026 |
|---|---|
| ISIN | IE00BLS09N40 |
| Asset Class | Equities |
| Base / Trading Currency | EUR / GBP |
| Inception Date | 8 December 2014 |
| Currency Hedged | No |
| Index Bloomberg Ticker | SX7T3L |
| Index Name | EURO STOXX Banks Daily Leverage 3 EUR Net Return Index |
| Leverage Factor | 3x |
Net Asset Value | As of 29/10/2026 |
|---|---|
| NAV | €65.660 |
| Daily Change | -€0.367 |
| Daily return | -0,556% |
| Total AUM of fund | 160.426.594 US$ |
| Issuer AUM | 3.582.455.933 US$ |
Structure
Structure | As of 29/10/2026 |
|---|---|
| Structure | ETP |
| Legal Structure | ETP |
| Replication Method | Fully Collateralised Swap |
| Domicile | Ireland |
| Physical Asset | Yes (Collateral) |
Further Legal and Tax Information | As of 29/10/2026 |
|---|---|
| ISA | Eligible |
| SIPP | Eligible |
| UCITS Eligible | Yes |
| UK Reporting Status | Yes |
| PEA Eligible | No |
Key Service Providers
Key Service Providers | As of 29/10/2026 |
|---|---|
| Custodian | Bank of New York Mellon |
| Administrator | Apex IFS Limited |
| Issuer | WisdomTree Multi Asset Issuer PLC |
| Auditor | Deloitte LLP |
| Trustee | Law Debenture Trust |
| Swap Provider | BNP Paribas Arbitrage SNC |
Fees | As of 29/10/2026 |
|---|---|
| Management Fee (MER) | 0,89% |
| Daily Swap Rate | 0,007330% |
Restrike | |
|---|---|
| Product intraday restrike threshold | 16,66% |
| Severe overnight gap event threshold | 25,00% |
| Product Restrike Information | Product Restrike Information |
Adverse price movements intraday or overnight can quickly and significantly reduce the value of a leveraged ETP, sometimes to zero. Understanding restrike arrangements is essential to understanding a key product risk.
Passported Countries
Listings & Codes
Country | Exchange | Trading Currency | Exchange Ticker | Bloomberg Ticker | RIC | SEDOL | ISIN | WKN | Settlement Period | Listing Date |
|---|---|---|---|---|---|---|---|---|---|---|
| LSE | GBx | 3BAL | 3BAL LN | WT3BAL.L | BTF7Z36 | IE00BLS09N40 | A14JCP | T + 2 | 15/03/2017 | |
| Borsa Italiana | EUR | 3BAL | 3BAL IM | 3BAL.MI | BLS09N4 | IE00BLS09N40 | A14JCP | T + 2 | 09/12/2014 | |
| Xetra | EUR | 0LJI | 0LJI GY | 0LJI.DE | BYSCBJ1 | IE00BLS09N40 | A14JCP | T + 2 | 30/06/2015 |
Index Details
EURO STOXX Banks Daily Leverage 3 EUR Net Return Index
The EURO STOXX Banks Daily Leverage 3 EUR Net Return Index aims to replicate the daily performance of the EURO STOXX Banks Net Return index multiplied daily by three and adjusted to reflect certain inherent costs of maintaining the leveraged positions required to achieve that aim. The EURO STOXX Banks Net Return index represents the largest companies belonging to the banks sector in the following Eurozone countries: Austria, Belgium, Finland, France, Germany, Ireland, Italy, Luxembourg, the Netherlands, Portugal and Spain.
Index Details | |
|---|---|
| Index Name | EURO STOXX Banks Daily Leverage 3 EUR Net Return Index |
| Currency | EUR |
| Index Provider | STOXX |
| Bloomberg Ticker | SX7T3L |
| Reuters Index Ticker | .SX7T3L |
| Leverage Factor | 3x |
Collateral Details
| Collateral Details | 22 May 2026 |
|---|---|
| Collateral Coverage Ratio | 105.3% |
| Collateralised | Yes |
| Over Collateralised | Yes |
| Custodian | Bank of New York Mellon |
Collateral Structure
Documents
Product
Prospectus
Reports and Regulatory
DISCLAIMERS
WisdomTree Multi Asset Issuer PLC (the “Issuer”) issues products under a Prospectus (“WTMA Prospectus”) approved by the Central Bank of Ireland, drawn up in accordance with the Directive 2003/71/EC. The WTMA Prospectus has been passported to various European jurisdictions including the UK, Italy and Germany and is available on this document.
WisdomTree Multi Asset Issuer PLC Exchange Traded Products (“ETPs”) are suitable for financially sophisticated investors who wish to take a view on the underlying indices and can understand the risks of investing in products offering leveraged or short exposures.
ETPs offering daily leveraged or daily short exposures (“Leveraged ETPs”) are products which feature specific risks that prospective investors should understand before investing in them. Higher volatility of the underlying indices and holding periods longer than a day may have an adverse impact on the performance of Leveraged ETPs. As such, Leveraged ETPs are intended for financially sophisticated investors who wish to take a short-term view on the underlying indices and understand such risks. As a consequence, WisdomTree is not promoting or marketing WisdomTree Multi Asset Issuer PLC ETPs to retail clients. Investors should refer to the section entitled "Risk Factors" and “Economic Overview of the ETP Securities” in the WTMA Prospectus for further details of these and other risks associated with an investment in Leveraged ETPs and consult their financial advisors as needed. Neither WisdomTree, nor the Issuer has assessed the suitability of any Leveraged ETPs for investors other than the relevant Authorised Participants.
While many leveraged WisdomTree Multi Asset Issuer PLC ETPs reset the leverage or short exposure on a daily basis, certain WisdomTree Multi Asset Issuer PLC ETPs utilise leverage in longer term strategies, where leveraged exposures may be reset monthly. These products are also only suitable for financially sophisticated investors who have understood the specific risks within the prospectus of the relevant product.
The EURO STOXX Banks Daily Leverage 3 EUR Net Return Index (the “Index”) is the intellectual property (including registered trademarks) of STOXX Ltd., ISS STOXX Index GmbH, or their licensors, and is used under license. WisdomTree EURO STOXX Banks 3x Daily Leveraged is neither sponsored nor promoted, distributed or in any other manner supported by STOXX Ltd., ISS STOXX Index GmbH or their licensors, research partners or data providers and STOXX Ltd., ISS STOXX Index GmbH and their licensors, research partners or data providers do not give any warranty, and exclude any liability (whether in negligence or otherwise) with respect thereto generally or specifically in relation to any errors, omissions or interruptions in the Index or its data.